


Metabolic Disorders Therapeutics Market Size and Overview
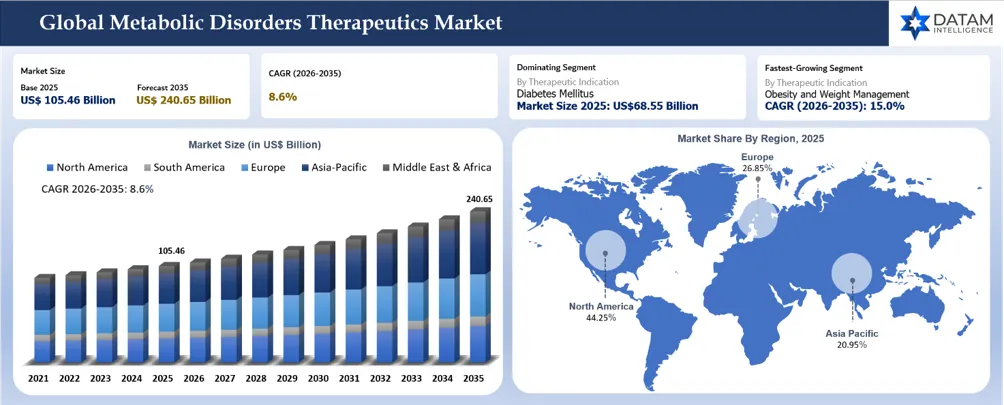
The global metabolic disorders therapeutics market reached US$105.46 billion in 2025 and is expected to reach US$240.65 billion by 2035, growing with a CAGR of 8.6% during the forecast period 2026-2035.
Market growth is increasingly driven by rising treatment penetration, expanding therapeutic indications and accelerating adoption of advanced metabolic medicines. Diabetes mellitus remains the largest therapeutic indication, supported by extensive utilization of insulin analogues, oral antidiabetic drugs, GLP-1 receptor agonists and SGLT2 inhibitors. Meanwhile, obesity and weight management is emerging as a major growth opportunity as dual GIP/GLP-1 agonists, oral incretin therapies and next-generation metabolic treatments reshape prescribing patterns. Increasing emphasis on cardiovascular protection, renal outcomes and sustained weight reduction is further strengthening demand for integrated cardiometabolic therapies.
The commercial expansion of Ozempic, Wegovy, Mounjaro and Zepbound has established incretin-based therapeutics as a major competitive force in metabolic disease management. Pharmaceutical manufacturers are expanding investments in oral GLP-1 formulations, multi-receptor agonists, long-acting injectables and combination therapies to improve treatment efficacy, convenience and persistence. Beyond diabetes and obesity, emerging treatments for MASH, dyslipidemia, gout and inherited metabolic disorders are creating additional opportunities for targeted therapies. Competitive differentiation increasingly depends on clinical outcomes, treatment durability, tolerability, pricing flexibility, reimbursement coverage and scalable manufacturing capabilities.
The next phase of market transformation will be shaped by precision metabolic medicine, disease-modifying therapies and integrated treatment strategies addressing multiple metabolic complications. RNA-based therapeutics, gene therapies, enzyme replacement technologies and novel metabolic targets could expand treatment possibilities for rare and previously underserved patient populations. Pharmaceutical companies are expected to prioritize strategic acquisitions, licensing partnerships, manufacturing capacity expansion and real-world evidence generation to strengthen commercialization. Long-term market leadership will depend on delivering measurable cardiovascular, hepatic and metabolic benefits while improving affordability, treatment adherence and patient access across developed and emerging markets.
Metabolic Disorders Therapeutics Market Key Takeaways
- Sustained Market Expansion Through 2035: The global metabolic disorders therapeutics market was valued at US$105.46 billion in 2025 and is projected to reach US$240.65 billion by 2035, registering a CAGR of 8.6% during 2026-2035, supported by rising metabolic disease prevalence, expanding treatment access and increasing adoption of advanced therapeutics.
- Diabetes Mellitus Maintains Market Leadership: Diabetes mellitus generated an estimated US$68.55 billion in 2025, accounting for approximately 65% of global market revenue, supported by widespread utilization of insulin analogues, oral antidiabetic drugs, GLP-1 receptor agonists and SGLT2 inhibitors, alongside increasing demand for long-term glycemic management.
- Obesity and Weight Management Emerges as the Primary Growth Engine: The obesity and weight management segment is projected to register an estimated 15% CAGR during 2026-2035, driven by accelerating adoption of GLP-1 receptor agonists, dual GIP/GLP-1 therapies, oral incretin formulations and expanding treatment eligibility across major pharmaceutical markets.
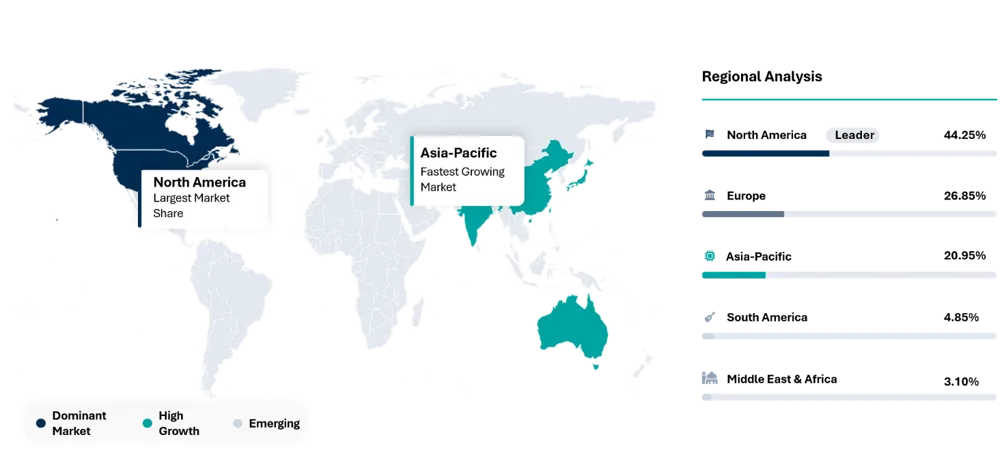
- North America Maintains Regional Dominance: North America accounted for an estimated 44.25% of global market revenue in 2025, equivalent to approximately US$46.67 billion, supported by strong adoption of branded incretin therapies, established pharmaceutical infrastructure, advanced specialty-care networks and comparatively high healthcare expenditure. Asia-Pacific is expected to offer significant long-term growth opportunities.
- Next-Generation Metabolic Therapies Reshape Competitive Strategy: Future market leadership will increasingly depend on differentiated weight reduction, durable glycemic control, cardiovascular and hepatic benefits, treatment convenience, long-term safety and reimbursement accessibility. Oral GLP-1 therapies, multi-receptor agonists, MASH-specific treatments, RNA-based medicines and gene-targeted therapeutics are expected to reshape treatment pathways, pharmaceutical investment priorities and competitive positioning through 2035.
Metabolic Disorders Therapeutics Market Industry Trends and Strategic Insights
- The market is transitioning from conventional glucose-lowering and symptom-focused treatments toward integrated, disease-modifying metabolic therapies addressing diabetes, obesity, dyslipidemia, MASH and associated cardiometabolic complications. Therapeutic value is increasingly assessed through sustained glycemic control, clinically meaningful weight reduction, cardiovascular and renal protection, hepatic improvement and long-term disease management outcomes.
- Diabetes mellitus remains the dominant therapeutic indication, supported by established utilization of insulin analogues, SGLT2 inhibitors, biguanides and incretin-based medicines. However, the rapid commercial expansion of GLP-1 receptor agonists and dual GIP/GLP-1 therapies is accelerating growth in obesity management, while oral formulations and expanding treatment eligibility are creating new opportunities for patient access and pharmaceutical revenue diversification.
- Next-generation incretin therapies are emerging as a major competitive growth driver, with pharmaceutical manufacturers advancing oral GLP-1 receptor agonists, triple-receptor agonists, long-acting injectables and combination regimens. Commercial adoption will increasingly depend on differentiated weight reduction, metabolic benefits, gastrointestinal tolerability, treatment persistence, manufacturing scalability and favorable reimbursement arrangements across major healthcare markets.
- Precision medicine and disease-modifying therapeutic platforms are reshaping opportunities across MASH, inherited metabolic disorders and refractory metabolic conditions. RNA-based medicines, enzyme replacement therapies, gene-targeted treatments and novel metabolic pathway modulators could expand treatment options for underserved patient populations. Their commercial success will depend on clinical validation, durable efficacy, regulatory approvals, specialized diagnostic infrastructure and sustainable market-access strategies.
- Sustainable competitive advantage will increasingly require pharmaceutical companies to demonstrate broader clinical and economic value beyond short-term metabolic improvements. Manufacturers combining cardiovascular and hepatic benefits, convenient administration, competitive pricing, reliable supply chains and credible real-world evidence will be better positioned to secure physician adoption, formulary inclusion and favorable reimbursement while capturing emerging opportunities across developed and high-growth regional markets.
Metabolic Disorders Therapeutics Market Scope
| Metrics | Details | |
| 2025 Market Size | US$105.46 Billion | |
| 2035 Projected Market Size | US$240.65 Billion | |
| CAGR (2026-2035) | 8.6% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Therapy Type | Small-Molecule Therapeutics, Peptide-Based Therapeutics, Protein-Based Therapeutics, Monoclonal Antibody Therapeutics, Enzyme Replacement Therapeutics, Oligonucleotide-Based Therapeutics, Gene Therapies, Cell-Based Therapies, Others | |
| By Therapeutic Indication | Diabetes Mellitus, Obesity and Weight Management, Dyslipidemia, Metabolic Dysfunction-Associated Steatohepatitis (MASH), Inherited Metabolic Disorders, Gout and Hyperuricemia | |
| By Drug Class | Insulins and Insulin Analogues, Biguanides, Sulfonylureas and Meglitinides, Sodium-Glucose Cotransporter-2 (SGLT2) Inhibitors, Dipeptidyl Peptidase-4 (DPP-4) Inhibitors, Thiazolidinediones, Alpha-Glucosidase Inhibitors, Incretin-Based Therapies, Lipid-Modifying Agents, Thyroid Hormone Receptor-Beta Agonists, Enzyme Replacement Therapies, Substrate Reduction Therapies, Metabolic Cofactor and Substrate Therapies, Others | |
| By Treatment Line | First-Line Therapy, Second-Line Therapy, Third-Line and Subsequent Therapy | |
| By Patient Age Group | Pediatric, Adult, Geriatric | |
| By Route of Administration | Oral, Subcutaneous, Intravenous, Intramuscular, Other Routes | |
| By Prescription Type | Prescription, Over-the-Counter | |
| By End User | Hospitals, Specialty Clinics, Ambulatory Care Centers, Home Care, Others | |
| By Distribution Channel | Hospital Pharmacies, Retail Pharmacies, Specialty Pharmacies, Online Pharmacies, Direct-to-Patient Channels, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | Israel, Saudi Arabia, UAE, Turkiye, South Africa, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Why does this report matter in 2026?
The global metabolic disorders therapeutics market is entering a pivotal phase in 2026, driven by the convergence of rising chronic disease prevalence, expanding therapeutic innovation and increasing healthcare expenditure. According to the International Diabetes Federation’s 2025 Diabetes Atlas, approximately 589 million adults worldwide were living with diabetes, with 252 million remaining undiagnosed, highlighting substantial unmet treatment needs. Commercial momentum is accelerating as GLP-1 receptor agonists and multi-receptor therapies reshape diabetes and obesity management. Eli Lilly reported combined Mounjaro and Zepbound revenues of approximately US$36.5 billion in 2025, demonstrating the commercial scale of incretin-based therapeutics.
In this evolving therapeutic and commercial landscape, the report provides critical intelligence for pharmaceutical manufacturers, investors and healthcare stakeholders navigating intensifying competition and changing treatment pathways. In the first quarter of 2026, Eli Lilly's Mounjaro revenue increased 125% year-on-year to US$8.7 billion, reflecting sustained demand for advanced metabolic therapies. Beyond diabetes and obesity, emerging opportunities in MASH, dyslipidemia and rare inherited metabolic disorders are broadening the competitive landscape. The report evaluates therapeutic innovation, pipeline differentiation, regulatory developments, reimbursement dynamics and geographic commercialization opportunities, enabling stakeholders to prioritize investments, identify underserved patient populations and develop evidence-based market entry and portfolio expansion strategies.
Metabolic Disorders Therapeutics Market White Space & Investment Opportunities
- Early Diagnosis and Precision Metabolic Risk Stratification: Invest in biomarker-based screening, continuous metabolic monitoring, genomic profiling and AI-enabled risk prediction to identify undiagnosed diabetes, dyslipidemia, MASH and inherited metabolic disorders earlier. Integrating predictive diagnostics with personalized treatment pathways offers opportunities to improve patient identification, therapeutic intervention and long-term disease management.
- Next-Generation Incretin and Multi-Target Therapeutics: Advance oral GLP-1 receptor agonists, dual GIP/GLP-1 agonists, triple-receptor agonists and combination therapies addressing obesity, insulin resistance and associated cardiometabolic complications. Significant investment opportunities exist in improving treatment durability, tolerability, dosing convenience and access while differentiating products beyond weight reduction through broader metabolic and cardiovascular outcomes.
- Disease-Modifying Therapies for Rare Inherited Metabolic Disorders: Accelerate development of gene therapies, RNA-based therapeutics, enzyme replacement therapies and substrate reduction treatments targeting lysosomal storage disorders, amino acid metabolism disorders, mitochondrial diseases and other inherited metabolic conditions. High unmet medical needs, limited disease-modifying alternatives and orphan-drug incentives create attractive opportunities for specialized pharmaceutical companies and strategic investors.
- Integrated Treatment of Metabolic Comorbidities: Develop therapies addressing overlapping metabolic conditions, including obesity, type 2 diabetes, dyslipidemia and MASH, through coordinated treatment strategies and differentiated mechanisms of action. Opportunities exist in combination regimens, organ-protective therapies and clinical programs demonstrating improvements in glycemic control, liver health, cardiovascular risk and sustainable metabolic outcomes.
- Long-Term Treatment Optimization and Real-World Evidence: Invest in comparative effectiveness studies, personalized treatment sequencing, adherence-support solutions and real-world evidence platforms to optimize the use of incretin therapies, insulin analogues, lipid-modifying drugs and emerging metabolic treatments. Addressing treatment discontinuation, weight regain, variable therapeutic responses and long-term safety uncertainties offers opportunities for product differentiation and value-based commercialization.
- Emerging Market Access and Value-Based Reimbursement: Expand access to affordable metabolic therapeutics across Asia-Pacific, Latin America and underserved healthcare systems through localized manufacturing, differentiated pricing, strategic distribution partnerships and patient-support programs. Investment opportunities also exist in generating health-economic evidence demonstrating reduced disease complications, hospitalization costs and long-term healthcare expenditure to strengthen reimbursement negotiations and improve treatment penetration.
Metabolic Disorders Therapeutics Market Future Transformation
The global metabolic disorders therapeutics market is poised for a structural transformation as treatment strategies evolve from conventional symptom management toward precision-driven, disease-modifying and multi-target therapeutic approaches. Next-generation GLP-1 receptor agonists, dual and triple incretin agonists, oral peptide therapies and combination regimens are expected to reshape the management of diabetes, obesity and associated cardiometabolic complications. Simultaneously, advances in RNA-based therapeutics, gene editing, enzyme replacement and substrate reduction technologies will expand treatment possibilities for rare inherited metabolic disorders. Increasing emphasis on metabolic biomarkers, genetic profiling and individualized treatment selection will accelerate the transition toward more targeted interventions, improved therapeutic durability and broader clinical benefits.
Over the next decade, competitive advantage will increasingly depend on demonstrating sustained clinical outcomes, improving patient access and delivering measurable healthcare value. Pharmaceutical companies are expected to prioritize integrated metabolic treatment portfolios, strategic licensing partnerships and acquisitions targeting differentiated therapeutic platforms. The expansion of oral therapies, personalized dosing strategies and digitally supported treatment monitoring will strengthen adherence and long-term disease management. Meanwhile, evolving reimbursement frameworks, pricing competition and greater emphasis on cardiovascular, renal and hepatic outcomes will influence commercialization strategies. Companies combining clinical differentiation, scalable manufacturing and evidence-based reimbursement strategies will be better positioned to capture emerging opportunities across developed and underserved markets.
Metabolic Disorders Therapeutics Market Buyer Decision-Making Criteria
Major Buyer Decision-Making Criteria:
- Magnitude and Durability of Metabolic Disease Control
- Effectiveness in Glycemic Control, Weight Reduction and Lipid Management
- Cardiovascular, Renal and Hepatic Clinical Benefits
- Speed of Therapeutic Response and Time to Clinical Improvement
- Long-Term Treatment Sustainability and Risk of Disease Recurrence
- Effectiveness Across Disease Severity Levels and Metabolic Comorbidities
- Safety, Tolerability and Long-Term Clinical Evidence
- Suitability Across Age Groups, Patient Profiles and Treatment Lines
- Route of Administration, Dosing Convenience and Treatment Adherence
- Monitoring Requirements, Drug Interactions and Contraindications
- Improvement in Patient Quality of Life and Long-Term Health Outcomes
- Pricing, Cost-Effectiveness, Reimbursement and Healthcare Budget Impact
- Clinical Guideline Recommendations, Physician Experience and Real-World Evidence
- Drug Availability, Supply Chain Reliability and Patient-Support Services
Metabolic Disorders Therapeutics Market Investment Trends
- Capital allocation is increasingly shifting toward next-generation GLP-1 receptor agonists, dual GIP/GLP-1 agonists, triple-receptor agonists and oral metabolic therapies, as pharmaceutical companies prioritize differentiated treatments for diabetes, obesity and associated cardiometabolic complications.
- Investment in precision medicine and disease-modifying therapeutics is expanding across gene therapies, RNA-based treatments, enzyme replacement therapies and substrate reduction approaches targeting lysosomal storage disorders, mitochondrial diseases and other rare inherited metabolic conditions with substantial unmet medical needs.
- Pharmaceutical companies are strengthening investment in integrated cardiometabolic treatment portfolios targeting obesity, type 2 diabetes, dyslipidemia and MASH, with increasing emphasis on therapies demonstrating cardiovascular protection, improved liver outcomes, sustained weight management and long-term metabolic benefits.
- Investors are increasingly prioritizing therapeutic assets offering differentiated efficacy, improved safety, convenient administration and durable treatment responses, particularly oral incretin therapies, long-acting injectables and combination regimens capable of improving adherence and addressing multiple metabolic risk factors.
- Digital-health investment is expanding toward AI-enabled metabolic risk assessment, continuous glucose monitoring integration, remote patient management, biomarker-based treatment optimization and predictive analytics platforms designed to improve early diagnosis, therapeutic personalization and long-term disease monitoring.
- Pharmaceutical manufacturers and healthcare investors are allocating greater resources to strategic licensing, biotechnology acquisitions, manufacturing capacity expansion, real-world evidence generation and health-economic studies. Investment priorities increasingly emphasize scalable production, reimbursement access, treatment affordability and measurable reductions in metabolic complications and long-term healthcare costs.
Strategic Indicators for Global Metabolic Disorders Therapeutics Market
High Regulation Impact
The global metabolic disorders therapeutics market faces substantial regulatory scrutiny due to the chronic nature of diabetes, obesity, dyslipidemia, MASH and inherited metabolic conditions, which often require prolonged or lifelong treatment. Regulatory authorities increasingly evaluate therapies based on glycemic control, weight reduction, lipid improvement, liver histology, cardiovascular outcomes, long-term safety and treatment durability. The FDA's 2024 approval of Rezdiffra for MASH and the subsequent expansion of therapeutic options have strengthened regulatory expectations for disease-specific clinical evidence. Developers must address gastrointestinal tolerability, hypoglycemia, hepatic safety, cardiovascular risks, drug interactions and post-marketing surveillance requirements. For rare metabolic disorders, gene and enzyme-based therapies face additional scrutiny regarding durability, immunogenicity and long-term effectiveness. These requirements increase development complexity and investment costs while favoring manufacturers with robust clinical trial capabilities, regulatory expertise and established pharmacovigilance infrastructure.
High Investment Activity
Investment activity is intensifying as pharmaceutical manufacturers, biotechnology companies and institutional investors expand exposure to metabolic therapeutic categories. Capital deployment is increasingly concentrated in next-generation GLP-1 receptor agonists, dual and triple incretin agonists, oral obesity therapies, MASH-specific treatments and precision therapeutics for inherited metabolic disorders. Pharmaceutical companies are prioritizing strategic licensing, biotechnology acquisitions, clinical pipeline expansion and manufacturing investments to strengthen competitive positioning. Growing demand for injectable and oral metabolic treatments is encouraging investment in peptide manufacturing, active pharmaceutical ingredient capacity and advanced drug-delivery platforms. Meanwhile, rare metabolic diseases are attracting specialized investment through orphan-drug development, RNA-based therapeutics and gene therapy platforms. Investment decisions increasingly depend on differentiated clinical outcomes, intellectual property protection, regulatory probability of success, reimbursement potential and scalable commercialization capabilities.
High New Drug-Class Adoption
The metabolic disorders therapeutics market is witnessing accelerated adoption of novel drug classes as treatment paradigms shift toward integrated metabolic control and disease-modifying interventions. GLP-1 receptor agonists, dual GIP/GLP-1 agonists and emerging multi-receptor therapies are gaining importance through their ability to address weight management, glycemic regulation and broader cardiometabolic risks. The FDA's April 2026 approval of Foundayo (orforglipron), an oral GLP-1 receptor agonist, highlights the expanding commercial potential of non-injectable metabolic treatments. Meanwhile, thyroid hormone receptor-beta agonists are establishing new treatment pathways for MASH, while RNA-based medicines, enzyme replacement therapies and gene-targeted approaches are expanding options for inherited metabolic disorders. Future adoption will depend on comparative efficacy, cardiovascular and hepatic benefits, tolerability, treatment convenience, long-term outcomes and payer acceptance. Manufacturers must demonstrate meaningful clinical differentiation to secure competitive positioning.
Regional Expansion Opportunity
Regional expansion opportunities remain substantial as the global burden of metabolic diseases continues to outpace diagnosis, treatment penetration and healthcare access across several emerging economies. North America remains a commercially important market due to established pharmaceutical infrastructure, specialist availability, advanced reimbursement systems and adoption of premium metabolic therapies. Europe presents opportunities through expanding chronic disease management programs, evolving clinical guidelines and increasing demand for cost-effective treatments, although country-specific pricing negotiations and health technology assessments influence market access. Asia-Pacific offers significant expansion potential, particularly across China, India and Japan, supported by large patient populations, improving diagnostic capabilities and expanding pharmaceutical manufacturing. Latin America and the Middle East also present opportunities for affordable diabetes, obesity and lipid-management therapeutics. Successful geographic expansion will depend on localized pricing strategies, regulatory approvals, physician engagement, reliable distribution networks and stronger patient affordability programs.
Government Policy Support
Government policies are increasingly influencing metabolic therapeutics development, treatment accessibility and long-term disease management through regulatory initiatives, national noncommunicable disease strategies, reimbursement reforms and public healthcare investment. In December 2025, the World Health Organization issued its first global guideline on GLP-1 therapies for obesity, conditionally recommending their long-term use in eligible adults alongside comprehensive lifestyle interventions. Such initiatives are strengthening policy recognition of obesity as a chronic disease requiring sustained clinical management. Regulatory incentives for orphan drugs and accelerated development pathways are also supporting therapeutic innovation for rare inherited metabolic conditions. However, government-funded healthcare systems continue to face affordability challenges associated with high-cost biologics, incretin therapies and gene-based treatments. Manufacturers must align commercialization strategies with national treatment guidelines, essential medicine priorities, health technology assessments and evidence-based reimbursement frameworks to secure sustainable market access.
Value-Based Pricing Intelligence
Value-based pricing is becoming increasingly important as healthcare payers evaluate metabolic therapeutics against clinical outcomes, treatment durability and total healthcare expenditure rather than short-term biomarker improvements alone. For diabetes and obesity treatments, reimbursement assessments increasingly consider sustained glycemic control, weight reduction, cardiovascular risk reduction, renal protection and treatment adherence. MASH therapies require evidence of meaningful liver-related benefits, while rare metabolic disorder treatments must demonstrate functional improvement, reduced disease progression and durable clinical effectiveness. Pricing differentiation will increasingly depend on comparative effectiveness, long-term safety, dosing convenience, patient eligibility and the ability to reduce hospitalization and complication-related costs. Manufacturers are expected to expand real-world evidence generation, pharmacoeconomic modeling and outcomes-based reimbursement discussions to support premium pricing. Companies demonstrating measurable clinical value alongside treatment affordability and reliable supply will be better positioned to secure formulary inclusion, broader reimbursement coverage and sustainable commercial growth.
AI Impact Analysis of Metabolic Disorders Therapeutics Market
Artificial intelligence is emerging as a strategic enabler in the global metabolic disorders therapeutics market, accelerating drug discovery, improving clinical development efficiency and supporting precision-based treatment strategies. AI-driven molecular modeling, predictive analytics and biomarker discovery are helping pharmaceutical companies identify therapeutic targets across diabetes, obesity, dyslipidemia, MASH and inherited metabolic disorders. Machine learning algorithms are increasingly being explored to optimize patient stratification, predict treatment responses and identify individuals at elevated risk of metabolic complications. Integration of AI with genomic datasets, electronic health records and continuous glucose monitoring systems is strengthening opportunities for personalized therapeutic selection, improved disease monitoring and earlier intervention, potentially reducing development inefficiencies and enhancing clinical outcomes.
From a commercial perspective, AI is expected to transform clinical trial recruitment, treatment adherence, pharmacovigilance and pharmaceutical portfolio optimization. Predictive models can support identification of eligible patients, simulation of clinical outcomes and assessment of drug safety risks, potentially reducing development costs and accelerating regulatory submissions. In January 2026, the FDA and European Medicines Agency introduced 10 guiding principles for responsible AI use in drug development, strengthening regulatory expectations for model reliability and evidence quality. Pharmaceutical companies integrating validated AI platforms with clinical research, real-world evidence and patient-support infrastructure could gain advantages in development efficiency, therapeutic differentiation and market access. However, data privacy, algorithmic bias and clinical validation remain critical implementation challenges.
Disruption Analysis of Metabolic Disorders Therapeutics Market
The global metabolic disorders therapeutics market is undergoing significant disruption as next-generation therapies challenge established treatment models, competitive structures and pharmaceutical revenue streams. The rapid adoption of GLP-1 receptor agonists, dual GIP/GLP-1 agonists and emerging multi-target therapies is reshaping diabetes and obesity management while increasing competitive pressure on conventional glucose-lowering and weight-management drugs. Oral incretin therapies, long-acting formulations and combination treatments are further challenging injectable-dominated treatment pathways by improving administration convenience and potentially expanding patient accessibility. Simultaneously, advances in RNA-based medicines, gene therapies and disease-modifying treatments are creating opportunities to address underlying metabolic dysfunction rather than relying exclusively on lifelong symptom management.
From a strategic perspective, market disruption will increasingly extend beyond therapeutic innovation to pricing models, manufacturing economics, reimbursement frameworks and pharmaceutical distribution channels. The introduction of oral GLP-1 therapies, including the FDA-approved Foundayo in April 2026, is intensifying competition around treatment convenience, affordability and patient accessibility. Patent expirations, generic competition and expanding biosimilar availability could further pressure established product revenues, encouraging portfolio diversification and strategic acquisitions. Meanwhile, direct-to-patient distribution, digital prescribing platforms and outcomes-based reimbursement are challenging conventional commercialization approaches. Pharmaceutical companies that combine differentiated clinical evidence, scalable production, competitive pricing and integrated patient-support capabilities will be better positioned to protect market share, capture underserved populations and navigate the evolving metabolic therapeutics landscape.
Metabolic Disorders Therapeutics Market BCG Matrix: Company Evaluation
STAR
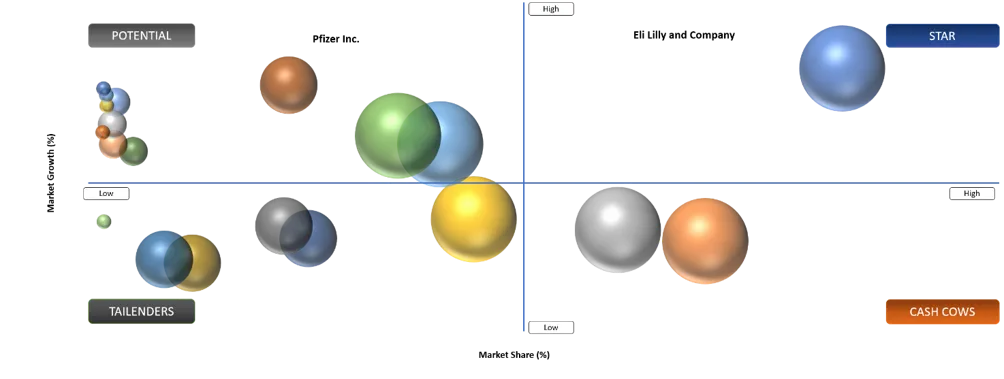
Eli Lilly and Company, Novo Nordisk A/S, AstraZeneca PLC and Boehringer Ingelheim International GmbH are positioned in the Star category based on their established commercial portfolios, strong market presence, expanding therapeutic indications and strategic influence across diabetes, obesity and cardiometabolic disease management. Eli Lilly maintains a leading competitive position through Mounjaro and Zepbound, while Novo Nordisk strengthens its market presence through Ozempic, Wegovy and Rybelsus. Both companies are driving the commercial expansion of incretin-based therapies through differentiated clinical outcomes, manufacturing investments and geographic commercialization strategies.
AstraZeneca and Boehringer Ingelheim reinforce their competitive positions through established SGLT2 inhibitor franchises, including Farxiga/Forxiga and Jardiance, respectively, which address diabetes and associated cardiovascular and renal complications. Their diversified cardiometabolic portfolios and established physician networks support sustained therapeutic adoption. Future leadership will increasingly depend on next-generation incretin development, oral treatment innovation, cardiovascular and hepatic benefits, competitive pricing, reimbursement access and manufacturing scalability. Companies demonstrating superior long-term outcomes, broader treatment eligibility and strong patient retention will be better positioned to defend commercial leadership.
POTENTIAL
Pfizer Inc., F. Hoffmann-La Roche Ltd, GSK plc, Madrigal Pharmaceuticals, Inc., Alnylam Pharmaceuticals, Inc., Ionis Pharmaceuticals, Inc. and BioMarin Pharmaceutical Inc. are positioned in the Potential category based on their emerging metabolic therapeutic pipelines, differentiated treatment platforms and opportunities to expand into underserved metabolic disease populations. Pfizer is strengthening its obesity pipeline through the acquisition of Metsera, with long-acting GLP-1 candidates and combination therapies targeting improved efficacy and dosing convenience. Roche is advancing enicepatide (CT-388) and petrelintide, with clinical programs exploring dual incretin and amylin-based approaches. GSK is progressing efimosfermin alfa for MASH, positioning itself within the evolving metabolic liver disease treatment landscape.
Madrigal is expanding its commercial presence through Rezdiffra while pursuing additional MASH therapeutic opportunities. Alnylam and Ionis are leveraging RNA-targeted platforms to address genetically defined metabolic conditions, while BioMarin is strengthening its rare metabolic disease portfolio through enzyme replacement and other specialized therapies. These companies offer differentiated opportunities across obesity, metabolic liver disease, lipid disorders and inherited metabolic conditions. Progression toward the Star category will depend on successful clinical development, regulatory approvals, commercial revenue expansion, differentiated therapeutic outcomes, favorable reimbursement and scalable manufacturing. Strategic partnerships, licensing agreements and geographic expansion will remain important drivers of future competitive positioning.
Metabolic Disorders Therapeutics Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Rapid Commercial Expansion of GLP-1 and Dual GIP/GLP-1 Therapeutics | 16.8% | Very high across North America and Europe; accelerating across Asia-Pacific | Type 2 diabetes, obesity and associated cardiometabolic complications | Expands premium therapeutic adoption, increases treatment penetration and drives investment in next-generation incretin portfolios |
Expansion of Oral Incretin Therapies and Multi-Receptor Agonist Pipelines | 14.5% | High in the United States and Europe; growing across China, Japan and other Asian markets | Patients requiring non-injectable obesity and diabetes treatments, including those facing injectable adherence barriers | Broadens treatment accessibility, strengthens product differentiation and creates new opportunities for oral formulations and combination therapies |
Emergence of Disease-Modifying Therapies for MASH and Rare Metabolic Disorders | 12.7% | Concentrated in North America and Europe; expanding across Japan and selected Asia-Pacific markets | MASH with moderate-to-advanced fibrosis, lysosomal storage disorders and inherited metabolic diseases | Unlocks previously underserved treatment populations, supports specialty-drug commercialization and attracts investment in precision therapeutics |
Growing Reimbursement Recognition of Cardiovascular, Renal and Hepatic Outcomes | 11.9% | Strongest across the United States, Western Europe and Japan; emerging in other healthcare systems | Metabolic patients with cardiovascular risk, chronic kidney disease, obesity-related complications and liver dysfunction | Strengthens value-based reimbursement, supports broader treatment eligibility and favors therapies demonstrating measurable long-term clinical and economic benefits |
Driver: Rapid Commercial Expansion of GLP-1 and Dual GIP/GLP-1 Therapeutics
The rapid commercial expansion of GLP-1 receptor agonists and dual GIP/GLP-1 therapeutics is a major growth driver for the Global Metabolic Disorders Therapeutics Market, fundamentally reshaping treatment strategies for type 2 diabetes, obesity and associated cardiometabolic complications. Increasing clinical adoption of semaglutide and tirzepatide is accelerating the transition from conventional glucose-lowering and weight-management therapies toward integrated metabolic treatments delivering sustained glycemic control, substantial weight reduction and broader cardiovascular benefits. Expanding regulatory indications, growing physician confidence and increasing patient awareness are strengthening prescription volumes across established pharmaceutical markets. Pharmaceutical manufacturers are simultaneously investing in manufacturing capacity, commercial infrastructure and geographic expansion to address growing therapeutic demand.
Commercial momentum is particularly evident in the performance of leading incretin franchises. In 2025, Eli Lilly reported combined global revenues of approximately US$36.5 billion from Mounjaro and Zepbound, highlighting the substantial revenue potential of differentiated metabolic therapies. Growing competition between Novo Nordisk, Eli Lilly and emerging developers is accelerating investment in oral formulations, next-generation multi-receptor agonists and improved delivery technologies. Over the forecast period, expanding treatment eligibility, stronger reimbursement coverage and improved production scalability are expected to support market penetration, while pricing pressures and long-term treatment persistence will increasingly determine competitive positioning and sustainable revenue growth.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
High Treatment Costs and Restrictive Reimbursement for Incretin Therapies | 15.6% | Patient affordability, formulary access and long-term treatment persistence | GLP-1 and dual GIP/GLP-1 therapies for obesity and type 2 diabetes, particularly among self-paying patients | Limits eligible patient conversion, increases treatment discontinuation and creates pressure for competitive pricing and outcomes-based reimbursement |
Gastrointestinal Adverse Events and Treatment Discontinuation in Incretin-Based Therapies | 13.8% | Treatment adherence, dose escalation and real-world effectiveness | Patients receiving GLP-1 and multi-receptor agonists for chronic obesity and glycemic management | Restricts long-term treatment persistence and increases demand for better-tolerated formulations and personalized dosing strategies |
Manufacturing Capacity Constraints and Supply Chain Complexity for Peptide Therapeutics | 12.4% | Product availability, manufacturing scalability and geographic commercialization | High-demand injectable incretin therapies requiring specialized peptide synthesis and sterile fill-finish capacity | Delays market penetration, increases capital expenditure and favors manufacturers with integrated production and dependable supply networks |
Limited Diagnosis and Complex Clinical Development for Rare Inherited Metabolic Disorders | 10.7% | Patient identification, clinical trial recruitment and specialty treatment access | Gene therapies, enzyme replacement therapies and RNA-based medicines for rare inherited metabolic diseases | Increases development costs, constrains addressable treated populations and necessitates specialized diagnostic networks and evidence generation |
Restraint: High Treatment Costs and Restrictive Reimbursement for Incretin Therapies
High treatment costs and restrictive reimbursement policies represent significant barriers to the expansion of the global metabolic disorders therapeutics market, particularly for GLP-1 receptor agonists and dual GIP/GLP-1 therapies used in diabetes and obesity management. Premium pricing, long-term treatment requirements and substantial out-of-pocket expenditure limit affordability, especially among uninsured and underinsured populations. Despite growing clinical evidence supporting glycemic control, weight reduction and cardiovascular benefits, reimbursement coverage remains inconsistent across healthcare systems. Payers frequently impose prior authorization, diagnosis-specific eligibility requirements and formulary restrictions to manage increasing pharmaceutical expenditure. These barriers constrain treatment initiation, reduce patient access and contribute to therapy discontinuation, particularly in price-sensitive markets.
The commercial impact extends beyond patient affordability, influencing pharmaceutical pricing strategies, prescribing patterns and long-term revenue sustainability. Manufacturers face increasing pressure to demonstrate cost-effectiveness, cardiovascular risk reduction and measurable improvements in healthcare utilization to justify premium pricing. Limited obesity-drug reimbursement across several public and private insurance programs further restricts market penetration despite substantial eligible patient populations. Expanding generic competition, negotiated pricing arrangements and outcomes-based reimbursement models could improve accessibility over time. However, companies must balance affordability initiatives with manufacturing investments, clinical development expenditure and profitability expectations to sustain commercialization and geographic expansion.
Metabolic Disorders Therapeutics Market Segment Analysis
The global metabolic disorders therapeutics market is segmented based on the therapy type, therapeutic indication, drug class, treatment line, patient age group, route of administration, prescription type, end user and distribution channel and region.
Diabetes Therapeutics Maintain Market Leadership While Obesity and Weight Management Emerges as the Fastest-Growing Segment
The diabetes mellitus segment dominates the global metabolic disorders therapeutics market, accounting for an estimated US$68.55 billion in 2025, representing approximately 65% of global market revenue. This dominance is supported by the substantial diagnosed and treated diabetic population, widespread utilization of insulin analogues, oral antidiabetic drugs, GLP-1 receptor agonists and SGLT2 inhibitors, and increasing demand for long-term glycemic management. Established pharmaceutical manufacturers, including Novo Nordisk, Eli Lilly, Sanofi and Boehringer Ingelheim, maintain strong commercial positions through diversified diabetes portfolios and expanding therapeutic indications. Growing emphasis on cardiovascular and renal protection, improved treatment adherence and personalized glucose management continues to strengthen segment revenue, while increasing generic competition and reimbursement scrutiny influence pricing strategies.
The obesity and weight management segment is projected to register the fastest growth, with an estimated 15% CAGR during 2026-2035, driven by accelerating adoption of GLP-1 receptor agonists, dual GIP/GLP-1 therapies and emerging oral incretin treatments. Expanding treatment eligibility, increasing physician prescribing and greater recognition of obesity as a chronic metabolic disease are supporting commercial penetration. Meanwhile, dyslipidemia, MASH, gout and inherited metabolic disorders present differentiated growth opportunities through targeted therapeutics, RNA-based medicines and disease-modifying approaches. Future segment performance will increasingly depend on clinical differentiation, reimbursement accessibility, manufacturing scalability and sustained therapeutic outcomes.
Metabolic Disorders Therapeutics Market Geographical Penetration
U.S. Metabolic Disorders Therapeutics Market Landscape
The U.S. metabolic disorders therapeutics market is experiencing significant commercial transformation, driven by increasing metabolic disease prevalence, rapid adoption of incretin-based therapies and expanding investment in precision therapeutics. According to the Centers for Disease Control and Prevention's 2026 update, approximately 40.1 million Americans have diabetes, highlighting substantial demand for effective long-term metabolic disease management. The treatment landscape is shifting toward GLP-1 receptor agonists, dual GIP/GLP-1 agonists and integrated cardiometabolic therapies offering benefits beyond conventional glycemic control. Commercial momentum remains strong, with Eli Lilly reporting approximately US$27.14 billion in combined U.S. Mounjaro and Zepbound revenues during 2025, reflecting expanding therapeutic adoption and premium treatment demand.
The competitive landscape is increasingly shaped by Novo Nordisk, Eli Lilly, Sanofi, AstraZeneca and specialized biotechnology companies developing treatments for MASH and inherited metabolic disorders. The FDA's April 2026 approval of oral orforglipron further strengthened innovation in convenient metabolic treatment options. However, restrictive reimbursement, treatment affordability and long-term adherence remain important commercialization challenges. Pharmaceutical companies are prioritizing differentiated clinical outcomes, manufacturing scalability, payer negotiations and strategic portfolio expansion to strengthen their competitive positioning and capture underserved patient populations.
Japan Metabolic Disorders Therapeutics Market Outlook
Japan's metabolic disorders therapeutics market is undergoing a significant transformation, supported by population aging, rising diabetes-related complications and growing adoption of advanced cardiometabolic treatments. According to Japan's Ministry of Health, Labour and Welfare, findings published in 2025 estimated approximately 11 million individuals strongly suspected of having diabetes, highlighting substantial demand for long-term metabolic disease management. The treatment landscape is evolving through expanding utilization of GLP-1 receptor agonists, dual GIP/GLP-1 therapies, SGLT2 inhibitors and precision therapeutics. Pharmaceutical companies are increasingly prioritizing treatments offering sustained glycemic control, weight management and cardiovascular protection. Japan's established specialty-care infrastructure and aging patient population provide opportunities for differentiated therapies addressing multiple metabolic complications.
The competitive landscape is shaped by Novo Nordisk, Eli Lilly, Takeda, Daiichi Sankyo and other international pharmaceutical manufacturers expanding their metabolic portfolios. Japan's universal health insurance system supports treatment access, although strict reimbursement criteria, government-regulated pharmaceutical pricing and periodic price revisions influence commercial profitability. The growing clinical importance of MASH, dyslipidemia and rare inherited metabolic disorders is encouraging investment in targeted medicines, genetic diagnostics and specialized treatment pathways. Over the forecast period, manufacturers demonstrating superior clinical outcomes, convenient administration, long-term safety and favorable pharmacoeconomic value will be better positioned to strengthen market penetration and secure sustainable revenue growth.
Global Metabolic Disorders Therapeutics Market Competitive Landscape
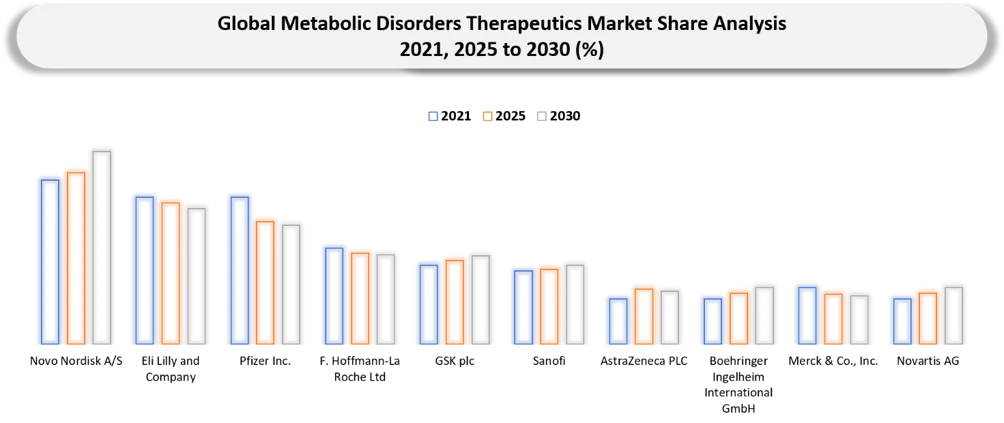
- The global metabolic disorders therapeutics market is characterized by intensifying competition among established pharmaceutical manufacturers, biotechnology innovators and specialty therapeutics developers pursuing differentiated opportunities across diabetes, obesity, dyslipidemia, MASH and inherited metabolic disorders. Novo Nordisk and Eli Lilly maintain strong commercial positions through their GLP-1 and dual GIP/GLP-1 portfolios, while Sanofi, AstraZeneca, Boehringer Ingelheim and Merck & Co. compete across established diabetes and cardiometabolic treatment categories. Pfizer, Roche and GSK are strengthening their competitive relevance through investments in next-generation obesity and metabolic liver disease pipelines. Competitive differentiation increasingly depends on therapeutic efficacy, cardiovascular and hepatic benefits, treatment convenience, manufacturing scalability and the ability to secure favorable reimbursement.
- Competition is increasingly extending into specialized and disease-modifying therapies, with BioMarin, Ultragenyx, Chiesi, Alnylam and Ionis targeting rare inherited metabolic disorders, while Madrigal strengthens competition in MASH therapeutics. Strategic acquisitions, licensing agreements and pipeline partnerships are becoming important mechanisms for securing differentiated assets and accelerating market entry. Pfizer's acquisition of Metsera in 2025 and Roche's advancement of incretin and amylin-based candidates in 2026 highlight intensifying investment in metabolic innovation. Over the forecast period, competitive advantage will increasingly depend on clinical differentiation, pricing flexibility, reimbursement access, intellectual property protection and supply chain reliability. Companies combining diversified metabolic portfolios with strong real-world evidence and scalable commercialization capabilities will be better positioned to defend market share and capture emerging therapeutic opportunities.
Key Companies of Metabolic Disorders Therapeutics Market
- Novo Nordisk A/S (Denmark)
- Eli Lilly and Company (United States)
- Pfizer Inc. (United States)
- F. Hoffmann-La Roche Ltd (Switzerland)
- GSK plc (United Kingdom)
- Sanofi (France)
- AstraZeneca PLC (United Kingdom)
- Boehringer Ingelheim International GmbH (Germany)
- Merck & Co., Inc. (United States)
- Novartis AG (Switzerland)
- Amgen Inc. (United States)
- Regeneron Pharmaceuticals, Inc. (United States)
- Takeda Pharmaceutical Company Limited (Japan)
- BioMarin Pharmaceutical Inc. (United States)
- Chiesi Farmaceutici S.p.A. (Italy)
- Madrigal Pharmaceuticals, Inc. (United States)
- Alnylam Pharmaceuticals, Inc. (United States)
- Ionis Pharmaceuticals, Inc. (United States)
- Ultragenyx Pharmaceutical Inc. (United States)
- Recordati S.p.A. (Italy)
Metabolic Disorders Therapeutics Market Major Pain Points
- Delayed Diagnosis and Uneven Patient Identification: Metabolic disorders frequently remain undiagnosed during early disease stages due to asymptomatic progression, limited screening infrastructure and fragmented referral pathways. Delayed detection of type 2 diabetes, dyslipidemia, MASH and inherited metabolic disorders reduces opportunities for timely intervention, increases complication risks and restricts access to appropriate therapeutic treatments, particularly in underserved healthcare systems.
- Complex Disease Progression and Multiple Metabolic Comorbidities: Metabolic disorders frequently coexist, with obesity, insulin resistance, dyslipidemia, gout and metabolic liver disease contributing to overlapping clinical complications. Progressive metabolic dysfunction, cardiovascular risks and renal impairment complicate disease management, requiring coordinated therapeutic strategies. The absence of integrated care pathways can increase treatment complexity, healthcare utilization and long-term disease burden.
- Heterogeneous Treatment Response and Limited Therapeutic Personalization: Differences in genetic predisposition, metabolic profiles, disease severity, age, comorbidities and previous treatment exposure contribute to variable responses across GLP-1 receptor agonists, insulin analogues, lipid-modifying agents and other metabolic therapeutics. Limited access to validated predictive biomarkers and personalized treatment algorithms complicates therapy selection, dose optimization and long-term clinical outcome management.
- Limited Disease-Modifying Options for Rare and Advanced Metabolic Disorders: Patients with inherited metabolic diseases, advanced MASH, refractory dyslipidemia and treatment-resistant gout often face restricted therapeutic alternatives. Although RNA-based medicines, enzyme replacement therapies and gene-targeted treatments are expanding treatment possibilities, high development costs, small eligible patient populations and uncertain long-term outcomes continue to limit availability and commercialization.
- Safety Concerns and Long-Term Treatment Burden: Chronic metabolic therapies often require prolonged administration, dose adjustments, laboratory monitoring and continuous clinical follow-up. Gastrointestinal adverse events associated with incretin therapies, hypoglycemia risks with certain glucose-lowering drugs, potential drug interactions and treatment-related complications can affect tolerability and adherence. Weight regain following treatment discontinuation and the need for sustained disease control further increase long-term treatment complexity.
- Limited Comparative Evidence and Uncertain Long-Term Clinical Outcomes: Differences in clinical trial populations, treatment duration, outcome measures and disease-specific endpoints complicate direct comparisons across metabolic therapeutics. Evidence gaps concerning long-term cardiovascular protection, hepatic improvement, treatment durability, metabolic complication reduction and real-world effectiveness create uncertainty for physicians, regulators and payers. These limitations make therapeutic differentiation, treatment sequencing and value-based reimbursement decisions increasingly challenging.
- Patient Adherence Challenges and Lifestyle-Related Treatment Barriers: Long-term treatment adherence remains a significant challenge due to complex medication regimens, injection-related concerns, dietary requirements, treatment fatigue and limited patient education. Obesity-related stigma, chronic disease distress and socioeconomic disparities can further discourage treatment initiation and persistence. Inadequate integration of pharmaceutical treatment with nutritional counseling, physical activity support and behavioral interventions may reduce sustained therapeutic effectiveness.
- High Treatment Costs and Restrictive Reimbursement Frameworks: Premium pricing of branded incretin therapies, enzyme replacement treatments, RNA-based medicines and emerging gene therapies creates substantial affordability challenges for patients and healthcare systems. Prior authorization, formulary restrictions, indication-specific reimbursement limitations and inconsistent insurance coverage constrain therapeutic access. Geographic disparities in drug availability, specialist infrastructure and pharmaceutical distribution further restrict treatment penetration, particularly across emerging and lower-income markets.
Metabolic Disorders Therapeutics Market Recent Developments
- October 2026: Madrigal Pharmaceuticals announced new clinical evidence demonstrating improvements in liver histology, fibrosis outcomes and metabolic biomarkers among patients receiving Rezdiffra (resmetirom), strengthening its therapeutic positioning in MASH management.
- September 2026: Roche reported positive Phase II clinical results for enicepatide (CT-388), an investigational dual GLP-1/GIP receptor agonist, demonstrating a 2.65-percentage-point reduction in HbA1c and 15.5% mean weight loss at the highest evaluated dose after 48 weeks.
- June 2026: Novo Nordisk announced that oral Wegovy (semaglutide) had surpassed 3 million prescriptions in the United States within approximately five months of launch, reflecting strong initial commercial adoption of oral GLP-1 obesity therapeutics.
- May 2026: Madrigal Pharmaceuticals reported first-quarter Rezdiffra net sales of approximately US$311.3 million, representing 127% year-on-year growth, highlighting increasing commercial adoption of MASH-specific therapeutics.
- April 2026: GSK announced that its investigational MASH therapy efimosfermin alfa received Breakthrough Therapy Designation from the U.S. FDA and PRIME designation from the European Medicines Agency, supporting its development for advanced metabolic liver disease.
- April 2026: Eli Lilly and Company received U.S. FDA approval for Foundayo (orforglipron), a once-daily oral GLP-1 receptor agonist for chronic weight management in eligible adults, expanding non-injectable treatment options for obesity.
- January 2026: Novo Nordisk launched oral Wegovy in the United States following FDA approval in December 2025, expanding access to non-injectable semaglutide through pharmacies, telehealth providers and direct-to-patient distribution channels.
- December 2025: Novo Nordisk received U.S. FDA approval for once-daily oral Wegovy (semaglutide 25 mg) for chronic weight management in eligible adults, following clinical evidence demonstrating substantial weight reduction in the OASIS 4 trial.
- November 2025: Pfizer completed its acquisition of Metsera for approximately US$7.0 billion in upfront enterprise value, strengthening its obesity and cardiometabolic pipeline with long-acting GLP-1 receptor agonists, amylin analogs and combination therapy candidates.
- September 2025: Ionis Pharmaceuticals announced European Union approval of Tryngolza (olezarsen) for adults with genetically confirmed familial chylomicronemia syndrome, expanding RNA-targeted treatment options for rare inherited lipid metabolism disorders.
- August 2025: Novo Nordisk received U.S. FDA accelerated approval for Wegovy (semaglutide 2.4 mg) for adults with noncirrhotic MASH and moderate-to-advanced liver fibrosis, expanding its therapeutic applications beyond diabetes and obesity.
Analyst View / Opinion on Metabolic Disorders Therapeutics Market
- The market is transitioning from conventional glucose-lowering and symptom-focused treatments toward integrated, precision-based metabolic therapies delivering sustained glycemic control, clinically meaningful weight reduction, cardiovascular protection and improved long-term metabolic outcomes.
- GLP-1 receptor agonists and dual GIP/GLP-1 therapies, including Ozempic, Wegovy, Mounjaro and Zepbound, are reshaping diabetes and obesity treatment, while emerging oral incretin formulations and multi-receptor agonists are intensifying competition across high-growth therapeutic categories.
- Treatment selection will increasingly depend on metabolic disease severity, glycemic status, body mass index, cardiovascular and renal risks, hepatic complications, genetic predisposition, previous treatment response, safety profile, dosing convenience, affordability and individual patient preferences.
- Next-generation triple-receptor agonists, thyroid hormone receptor-beta agonists, RNA-based medicines, enzyme replacement therapies and gene-targeted treatments could diversify therapeutic options across obesity, MASH, dyslipidemia, gout and inherited metabolic disorders, creating opportunities for differentiated pharmaceutical portfolios.
- Sustainable market leadership will require clinical evidence demonstrating durable metabolic control, sustained weight reduction, reduced cardiovascular and hepatic complications, improved treatment adherence, manageable long-term safety and measurable improvements in patient quality of life and healthcare utilization.
- Commercial success will increasingly depend on manufacturing scalability, competitive pricing, reimbursement accessibility, integrated cardiometabolic treatment strategies, physician engagement, direct-to-patient distribution, strategic partnerships and real-world evidence demonstrating meaningful clinical and economic value across developed and emerging markets.
Metabolic Disorders Therapeutics Market Target Audience
| INDUSTRY | WHO SHOULD BUY THIS REPORT? | REASON TO BUY THIS REPORT |
| Pharmaceutical and Biotechnology Companies | Branded drug manufacturers, generic pharmaceutical companies, metabolic therapy developers and specialty biotechnology firms | Assess therapeutic opportunities across diabetes, obesity, dyslipidemia, MASH and inherited metabolic disorders; evaluate competitive positioning, product differentiation and commercialization potential. |
| Diagnostic and Digital-Health Companies | Molecular diagnostic developers, genomic testing companies, continuous glucose monitoring providers, AI-driven health platforms and clinical decision-support companies | Identify opportunities in metabolic biomarker testing, genetic screening, patient stratification, predictive monitoring and therapy optimization. |
| Healthcare Providers | Endocrinologists, diabetologists, obesity specialists, hepatologists, cardiologists, metabolic disease specialists, hospitals and specialty clinics | Understand emerging treatment pathways, drug-class adoption, patient eligibility, combination therapies and long-term metabolic disease management. |
| Payers and Market-Access Organizations | Health insurers, pharmacy benefit managers, health technology assessment agencies, reimbursement consultants and healthcare purchasing organizations | Evaluate comparative clinical effectiveness, treatment affordability, formulary positioning, reimbursement requirements and long-term healthcare budget impact. |
| Patient Advocacy and Support Organizations | Diabetes associations, obesity advocacy organizations, rare metabolic disease foundations, caregiver networks and patient-support groups | Understand unmet therapeutic needs, treatment accessibility, adherence barriers, patient affordability and quality-of-life outcomes. |
| Government and Regulatory Bodies | Drug regulatory agencies, public health authorities, national reimbursement agencies and healthcare policymakers | Support regulatory assessment, chronic disease management policies, treatment accessibility, pharmacovigilance and evidence-based reimbursement decisions. |
| Investors and Financial Institutions | Private equity firms, venture capital investors, institutional investors, investment banks and healthcare investment funds | Evaluate therapeutic pipeline value, commercial scalability, regulatory risks, licensing opportunities, strategic partnerships and acquisition prospects. |
| Market Research and Consulting Firms | Healthcare strategy consultancies, pharmaceutical competitive-intelligence teams, market access advisors and commercial research firms | Support market-entry planning, therapeutic portfolio strategy, competitive benchmarking, revenue forecasting and commercial due diligence. |
| Research Organizations | Clinical research organizations, academic institutions, universities, translational research centers and metabolic disease research institutes | Analyze clinical trial pipelines, emerging therapeutic mechanisms, biomarker development, patient recruitment and unmet research needs. |
| Specialty Pharmacies and Distributors | Specialty pharmacies, hospital pharmacies, pharmaceutical wholesalers, cold-chain logistics providers and home-delivery pharmacy networks | Assess distribution requirements, specialty drug handling, supply chain capacity, patient onboarding, treatment adherence and geographic access opportunities. |
Why Choose DATAM?
- Data-Driven Insights: Access granular Global Metabolic Disorders Therapeutics Market intelligence covering market size, therapeutic indication shares, drug-class adoption, diagnosed and treated populations, GLP-1 and dual GIP/GLP-1 utilization, clinical pipelines, competitive positioning, treatment penetration and regional reimbursement dynamics, supported by primary interviews with pharmaceutical executives, clinicians and industry experts.
- Post-Purchase Support and Expert Analyst Consultations: Engage directly with our healthcare analysts for customized guidance on therapeutic portfolio positioning, patient segmentation, treatment sequencing, competitive benchmarking, market entry, pricing strategies, reimbursement assessment and commercialization opportunities across diabetes, obesity, dyslipidemia, MASH and inherited metabolic disorders.
- White Papers and Case Studies: Receive periodic insights on next-generation incretin therapies, oral GLP-1 developments, multi-receptor agonists, MASH-specific treatments, RNA-based therapeutics, gene therapies, regulatory approvals, strategic partnerships and evolving physician prescribing patterns across major metabolic disease categories.
- Annual Updates on Purchased Reports: Stay informed through annual updates covering drug approvals, clinical trial readouts, therapeutic pipeline developments, indication expansions, patent expirations, licensing agreements, manufacturing investments, pricing changes, reimbursement developments and competitive landscape shifts. Terms and conditions apply.
- Specialized Focus on Emerging Markets: Gain country-specific intelligence on metabolic disease prevalence, diagnosed and treated populations, healthcare infrastructure, treatment affordability, GLP-1 adoption, specialty therapy accessibility, reimbursement frameworks and pharmaceutical commercialization opportunities across Asia-Pacific, Latin America, the Middle East and other high-growth emerging markets.
- Value of DataM Reports: Obtain customized strategic intelligence addressing critical business questions related to next-generation metabolic therapies, unmet treatment needs, patient eligibility, therapeutic differentiation, long-term treatment adherence, competitive pipeline disruption, market-access barriers, revenue opportunities and investment priorities, extending beyond conventional market databases to support evidence-based commercial decision-making.
What DATAM Uniquely Provides
- In-depth segmentation of the Global Metabolic Disorders Therapeutics Market by therapy type, therapeutic indication, drug class, treatment line, patient age group, route of administration, prescription type, end user, distribution channel and region, covering diabetes, obesity, dyslipidemia, MASH, gout and inherited metabolic disorders.
- Detailed competitive analysis of leading pharmaceutical and biotechnology companies covering GLP-1 receptor agonists, dual and triple incretin agonists, insulin analogues, lipid-modifying drugs, enzyme replacement therapies and emerging gene-based treatments, with emphasis on clinical efficacy, safety, treatment durability, pipeline maturity, pricing, market positioning and commercialization strategies.
- Comprehensive assessment of disease prevalence, diagnosed and treated populations, treatment-eligible patients, metabolic comorbidities, disease severity, treatment penetration, therapeutic switching patterns, adherence challenges and unmet clinical needs across major metabolic conditions, supported by regional epidemiological intelligence and patient-level treatment opportunity mapping.
- Actionable intelligence on pharmaceutical pricing, reimbursement restrictions, regulatory approvals, treatment accessibility, manufacturing capacity, direct-to-patient commercialization, strategic licensing, mergers and acquisitions, competitive partnerships and investment opportunities across established and emerging metabolic therapeutic categories.
- Data-driven market forecasts highlighting high-growth therapeutic indications, next-generation oral incretin therapies, multi-receptor agonists, MASH-specific drugs, RNA-based therapeutics, gene therapies and precision metabolic treatments, alongside regional expansion opportunities, patent expirations, emerging competitive threats and evolving treatment paradigms through 2035.



























































