


Biosimilars Market Size Overview
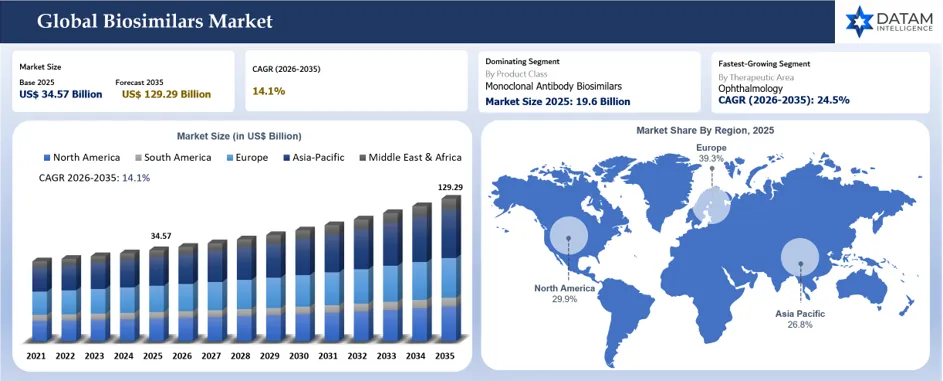
The global biosimilars market reached US$34.57 billion in 2025 and is expected to reach US$129.29 billion by 2035, growing with a CAGR of 14.1% during the forecast period 2026-2035.
Market expansion is being driven by the loss of exclusivity for high-value biologics, increasing pressure on healthcare systems to control treatment costs, and wider acceptance of biosimilars among physicians, payers and patients.
Competitive activity is intensifying across oncology, immunology, ophthalmology, hematology, diabetes and other specialty therapeutic areas. Monoclonal antibody biosimilars remain the largest product class, while ophthalmology is emerging as a high-growth opportunity supported by increasing competition around ranibizumab and aflibercept. Regulatory streamlining, stronger interchangeability frameworks and expanding payer support are improving commercialization prospects, although price erosion, patent litigation and manufacturing complexity remain important constraints.
The market is also shifting toward more complex molecules, differentiated delivery formats, regional manufacturing expansion and strategic licensing partnerships. Future competitive advantage will depend on molecule selection, launch timing, cost-efficient manufacturing, supply reliability, payer access and the ability to build diversified biosimilar portfolios across major regulated and emerging markets.
Biosimilars Market Key Takeaways
- Sustained Market Expansion Through 2035: The global biosimilars market was valued at US$34.57 billion in 2025 and is projected to reach US$129.29 billion by 2035, growing at a CAGR of 14.1% during 2026-2035, supported by biologic patent expiries, payer cost-containment and expanding regulatory approvals.
- Monoclonal Antibody Biosimilars Maintain Product-Class Leadership: Monoclonal antibody biosimilars accounted for an estimated 56.8% market share, equivalent to approximately US$19.6 billion in 2025, supported by established demand across oncology, immunology and other specialty therapies.
- Ophthalmology Emerges as a High-Growth Opportunity: Ophthalmology is expected to be among the fastest-growing therapeutic areas, with an estimated 24.5% CAGR during 2026-2035, driven by expanding ranibizumab and aflibercept biosimilar competition and increasing treatment demand for retinal diseases.
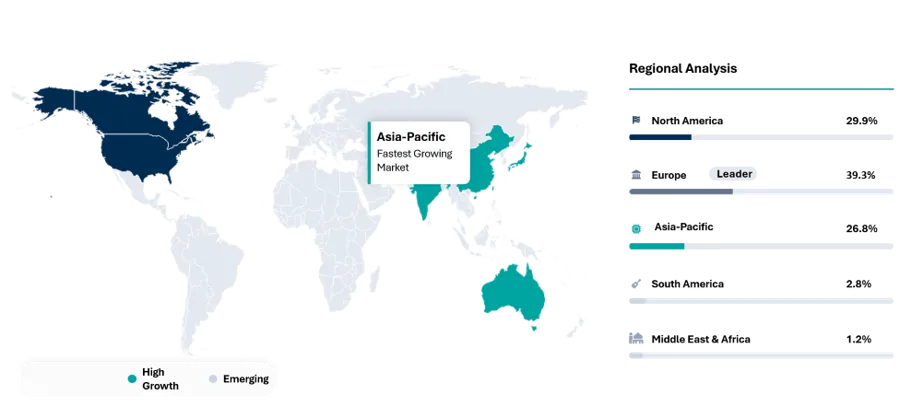
- Europe Maintains Regional Dominance: Europe accounted for an estimated 39.3% of the global market in 2025, supported by mature biosimilar regulations, tender-based procurement, established prescribing practices and strong payer-driven adoption. Asia Pacific represents a major growth opportunity through manufacturing scale and expanding domestic uptake.
- Competition Shifts Toward Next-Wave Molecules and Commercial Execution: Future leadership will increasingly depend on early positioning around high-value patent expiries, diversified pipelines, manufacturing economics, reliable supply, payer access and tender competitiveness. Complex biosimilars, differentiated delivery formats and strategic licensing partnerships are expected to reshape competitive positioning through 2035.
Biosimilars Market Industry Trends and Strategic Insights
- Regulatory Streamlining Is Accelerating Market Entry: Simplified development and approval pathways are lowering barriers for biosimilar manufacturers and supporting faster commercialization.
- Opportunity Is Expanding Beyond Core Therapy Areas: Growth is increasingly shifting from traditional oncology and immunology toward ophthalmology, diabetes, hematology, bone health, and other specialty indications.
- Patent Expiries Are Creating a Strong Future Pipeline: Upcoming loss of exclusivity for high-value biologics is opening sizeable opportunities for new biosimilar launches and portfolio expansion.
- Affordability Is Driving Broader Healthcare Adoption: Cost pressures across healthcare systems are strengthening payer, provider, and institutional preference for competitively priced biosimilar alternatives.
- Commercial Differentiation Is Becoming the Key Success Factor: Competitive advantage increasingly depends on pricing, formulary access, tender positioning, physician confidence, supply reliability, and strong market execution.
Biosimilars Market Scope
| Metrics | Details | |
| 2025 Market Size | US$34.57 Billion | |
| 2035 Projected Market Size | US$ 129.29 Billion | |
| CAGR (2026-2035) | 14.1% | |
| Largest Market | Asia-Pacific | |
| Fastest Growing Market | North America | |
| Product Class | Monoclonal Antibody Biosimilars; Fusion Protein Biosimilars; Insulin and Insulin Analog Biosimilars; Granulocyte Colony-Stimulating Factor Biosimilars; Erythropoiesis-Stimulating Agent Biosimilars; Human Growth Hormone Biosimilars; Gonadotropin Biosimilars; Other Recombinant Protein Biosimilars | |
| Molecule Complexity | Low-Complexity Recombinant Proteins; Moderate-Complexity Glycoproteins; High-Complexity Biologics; Very High-Complexity Multidomain Biologics | |
| Manufacturing Platform | Mammalian Cell-Based Manufacturing; Bacterial Cell-Based Manufacturing; Yeast-Based Manufacturing; Other Expression Platforms | |
| Therapeutic Area | Oncology; Autoimmune and Inflammatory Diseases; Diabetes and Metabolic Disorders; Ophthalmology; Hematology; Bone and Skeletal Disorders; Neurology; Allergy and Respiratory Diseases; Rare Diseases; Endocrine and Growth Disorders; Fertility and Reproductive Health; Others | |
| Route of Administration | Subcutaneous; Intravenous; Intravitreal; Intramuscular; Others | |
| Distribution Channel | Hospital Pharmacies; Specialty Pharmacies; Retail and Community Pharmacies; Direct Institutional Procurement; Others | |
| End User | Hospitals; Specialty Clinics; Infusion Centers; Ambulatory Care Centers; Homecare Settings; Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | Israel, Saudi Arabia, UAE, Turkiye, South Africa, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Why does this report matter in 2026?
In 2026, the global biosimilars market is entering a decisive growth phase as patent expiries for high-value biologics, expanding regulatory approvals and mounting healthcare cost pressures accelerate market participation. Competition is broadening beyond established oncology and immunology products into ophthalmology, diabetes, hematology, bone health and other specialty therapies, while development pipelines are increasingly targeting the next wave of complex and high-revenue biologics. Regulatory streamlining, growing payer support and wider physician familiarity are expected to improve commercialization opportunities, although pricing pressure, tender competition, interchangeability, supply reliability and market access remain critical success factors. This report matters because it establishes a clear market boundary, separates biosimilar revenues from originator biologics and generic drugs, and quantifies demand across product classes, reference molecules, therapeutic areas and regions without double counting.
The 2026 outlook is increasingly defined by a shift from regulatory approval-led growth toward portfolio scale, launch timing and commercial execution. Manufacturers are prioritizing molecules with attractive patent-expiry windows, sizeable addressable patient populations and manageable competitive intensity, while healthcare systems are pursuing greater biosimilar penetration to reduce biologic treatment expenditure. The report provides decision-makers with visibility into competitive positioning, pipeline opportunities, manufacturing platforms, pricing dynamics, market access and regional commercialization potential. Manufacturers can benchmark molecule opportunities, evaluate capacity requirements and identify attractive therapeutic segments, while investors and commercial teams can assess emerging competitors, adoption trends, regulatory exposure and the most promising growth opportunities across established and developing biosimilar markets.
Biosimilars Market White Space & Investment Opportunities
- Next-Wave High-Value Molecule Development: Prioritize biosimilars targeting upcoming patent expiries in oncology, immunology, ophthalmology, neurology and other specialty therapies where competition remains limited and revenue potential is substantial.
- Complex Biologics and Difficult-to-Replicate Molecules: Invest in technically demanding monoclonal antibodies, fusion proteins and other complex biologics where higher development barriers can support stronger competitive differentiation and more sustainable pricing.
- Emerging Market Commercial Expansion: Build localized regulatory, manufacturing and distribution capabilities across Asia Pacific, Latin America, Middle East and selected African markets where biosimilar penetration remains below mature-market levels.
- Integrated Manufacturing and Cost Optimization: Strengthen cell-line development, upstream processing, purification, fill-finish and analytical capabilities to reduce cost of goods, improve scalability and protect margins as price competition intensifies.
- Specialty and Hospital Channel Penetration: Develop stronger payer, hospital, specialty pharmacy and tender strategies to improve formulary access, physician adoption and institutional purchasing across high-volume biologic treatment categories.
- Portfolio Partnerships and Licensing: Pursue co-development, regional licensing, contract manufacturing and commercialization partnerships to accelerate market entry, broaden molecule portfolios and reduce the capital burden associated with global biosimilar development.
Biosimilars Market Future Transformation
Over the next decade, the global biosimilars market will evolve from a primarily cost-saving alternative into a central mechanism for expanding patient access to biologic therapies and improving healthcare affordability. As more high-value biologics lose exclusivity, biosimilar adoption is expected to broaden across oncology, immunology, ophthalmology, neurology, bone health and other specialty areas. Greater competition should enable more patients to access advanced biologic treatments, reduce financial barriers to therapy and support earlier or wider treatment use across constrained healthcare systems.
For payers and health systems, biosimilars will become increasingly important in controlling biologic drug expenditure, improving formulary efficiency and reallocating savings toward additional patients, new therapies and broader care delivery. Competitive dynamics will therefore shift beyond regulatory approval toward pricing sustainability, interchangeability, physician confidence, contracting, tender performance and reliable supply.
Manufacturing advances, including improved cell-line engineering, intensified bioprocessing, purification technologies and scalable production platforms, are expected to lower cost structures and strengthen supply continuity. Long-term market leadership will depend on delivering sustainable savings without compromising availability, while supporting payer objectives, physician adoption and broader patient access across both developed and emerging markets.
Biosimilars Market Buyer Decision-Making Criteria
Major Buyer Decision-Making Criteria:
- Comparative Quality and Analytical Similarity
- Regulatory Approval and Compliance Status
- Clinical and Real-World Evidence
- Pricing and Total Treatment Cost
- Reimbursement and Formulary Coverage
- Interchangeability and Substitution Status
- Physician Confidence and Patient Acceptance
- Manufacturing Quality and Supply Reliability
- Contracting, Tender and Volume-Based Pricing
- Product Presentation and Administration Convenience
- Pharmacovigilance and Safety Monitoring Support
- Manufacturer Reputation and Commercial Track Record
- Distribution Reach and Inventory Availability
- Patient Support and Education Programs
- Long-Term Supply and Procurement Security
Biosimilars Market Economic & Investment Analysis
The global biosimilars market is becoming an increasingly attractive pharmaceutical investment segment, supported by rising biologic treatment expenditure, expanding patent-expiry opportunities, healthcare cost-containment initiatives and broader payer acceptance. Investment opportunities are extending beyond established oncology and immunology biosimilars toward ophthalmology, diabetes, bone health, neurology and other specialty therapies. Competitive economics increasingly depend on reference-molecule selection, development timelines, manufacturing yield, regulatory execution, pricing discipline and the ability to achieve sufficient commercial scale before markets become highly competitive.
Investment is shifting toward next-wave biosimilar pipelines, complex biologics, high-productivity manufacturing platforms and regional commercialization capabilities. Leading participants such as Sandoz, Celltrion, Samsung Bioepis, Biocon Biologics, Amgen and Fresenius Kabi are strengthening portfolios through internal development, licensing, partnerships and geographic expansion. Future value creation will increasingly depend on securing early entry around loss-of-exclusivity windows, reducing cost of goods, achieving reliable manufacturing scale and gaining payer, formulary and tender access. Key investment risks include development expenditure, regulatory delays, aggressive price erosion, litigation, crowded molecule pipelines and supply-chain complexity. Companies combining differentiated portfolios, scalable manufacturing, strong regulatory capabilities and broad commercial reach are positioned to capture greater long-term value.
Biosimilars Market Investment Trends
- Capital allocation is increasing toward high-value biosimilar pipelines targeting upcoming patent expiries across oncology, immunology, ophthalmology, neurology, bone health and other specialty therapeutic areas.
- Investment is expanding into advanced biologics manufacturing capacity, including high-productivity cell lines, intensified bioprocessing, purification infrastructure, fill-finish capabilities and scalable production systems designed to reduce cost of goods and improve supply reliability.
- Investors are prioritizing complex and technically differentiated biosimilars, including monoclonal antibodies, fusion proteins and difficult-to-manufacture biologics where development barriers and lower competitive density can support stronger commercial positioning.
- Strategic capital is increasingly directed toward licensing, co-development and regional commercialization partnerships that allow biosimilar developers to expand geographic reach, accelerate regulatory entry and share development and commercialization risk.
- Investment is also shifting toward payer access, tender capabilities and commercial infrastructure, as future returns increasingly depend on formulary inclusion, contracting strength, physician adoption, reliable distribution and sustained market penetration rather than regulatory approval alone.
Strategic Indicators for the Global Biosimilars Market
High Regulation Impact
The biosimilars market is subject to intensive regulatory oversight because products must demonstrate robust comparability with an approved reference biologic across analytical quality, biological activity, manufacturing consistency, clinical performance, immunogenicity and pharmacovigilance requirements. Regulatory frameworks also influence interchangeability, substitution, labeling, post-marketing surveillance and commercialization strategies. In 2026, both the FDA and EMA are moving toward more efficient, science-based development pathways, including reduced reliance on unnecessary clinical studies where analytical comparability is sufficiently strong.
Regulatory requirements, however, remain region-specific, particularly around reference-product selection, interchangeability, substitution practices and market authorization. This increases development complexity and favors companies with strong analytical capabilities, regulatory expertise, validated manufacturing systems and global pharmacovigilance infrastructure. Regulatory execution therefore remains a major determinant of development cost, approval timing, market access and long-term competitiveness.
High Investment Activity
Investment activity in the global biosimilars market is accelerating across next-generation pipelines, advanced biologics manufacturing, purification, fill-finish capacity, and regional commercialization platforms. Capital is increasingly directed toward high-value reference molecules approaching patent expiry, particularly in oncology, immunology, ophthalmology, neurology, and other specialty therapies. Strategic interest is also rising in licensing, co-development, contract manufacturing, and cross-border commercialization partnerships that reduce development risk and accelerate market entry. Investors favor companies with scalable manufacturing, strong regulatory capabilities, diversified portfolios, reliable supply, and effective payer access. Key risks include development costs, litigation, regulatory delays, price erosion, and intense competition in crowded molecules globally today.
High New Product-Format Adoption
Biosimilar adoption is expanding beyond conventional vial-based presentations toward prefilled syringes, autoinjectors, on-body delivery systems, ready-to-use formulations, and higher-concentration subcutaneous products. These formats are improving administration convenience, reducing preparation requirements, and supporting greater use across outpatient and home-care settings. Manufacturers are increasingly using device-enabled presentations and differentiated dosing options to strengthen product positioning, improve patient experience, and compete beyond price alone. Demand is also rising for formulations that reduce infusion time, simplify storage, and improve handling efficiency. Future adoption will depend on regulatory approval, device reliability, patient preference, provider acceptance, reimbursement, and demonstrated operational benefits across healthcare settings.
Regional Expansion Opportunity
Regional expansion opportunities in the global biosimilars market remain substantial as regulatory pathways, biologic penetration, payer policies, pricing structures, and physician acceptance vary widely across countries. Europe remains a mature biosimilars market supported by established tender systems and strong institutional adoption, while the United States offers significant growth potential through expanding approvals, interchangeability, and payer-driven uptake. Asia Pacific, particularly India, China, South Korea, and Japan, is strengthening its position through manufacturing scale, domestic commercialization, and export-oriented biosimilar development. Latin America, the Middle East, and selected African markets offer additional opportunities as healthcare systems seek lower-cost biologic therapies. Successful expansion requires localized regulatory strategies, competitive pricing, reliable supply, strong distribution, and effective payer engagement.
Government Policy Support
Government support for biosimilars is strengthening through streamlined regulatory pathways, competition policies, reimbursement frameworks, interchangeability rules and public procurement programs. In 2026, regulators are increasingly focused on improving development efficiency while maintaining rigorous analytical, manufacturing and safety standards. FDA continues to refine biosimilar guidance, while EMA is reviewing its overarching biosimilar guideline to reflect advances in scientific and regulatory practice. Government-backed tendering, substitution policies and payer incentives can accelerate adoption and generate healthcare savings. Successful manufacturers require strong regulatory capabilities, pharmacovigilance systems, manufacturing compliance and market-specific reimbursement strategies to capture these opportunities.
Value-Based Pricing Intelligence
Value-based pricing in the biosimilars market increasingly depends on the measurable economic advantage delivered versus reference biologics rather than list-price discounts alone. Payers evaluate acquisition cost, treatment cost, contracting terms, tender discounts, administration requirements, supply reliability and potential healthcare-system savings. Pricing potential differs considerably across oncology, immunology, ophthalmology, diabetes and other specialty therapies depending on competitive intensity and available biosimilar alternatives. Manufacturers combining sustainable pricing with strong supply continuity, convenient product formats, payer contracting and physician confidence can achieve stronger market penetration. As more competitors enter established molecules, pricing intelligence, tender strategy and portfolio differentiation will become increasingly important for protecting margins and sustaining long-term commercial value.
Disruption Analysis of Biosimilars Market
The biosimilars market is being disrupted by regulatory streamlining, accelerating biologic patent expiries, intense price compression and rapid expansion of competing pipelines. As more manufacturers enter established molecules, competition is shifting from regulatory approval alone toward launch timing, manufacturing economics, payer access, tender performance and supply reliability. Increased use of analytical comparability and potentially reduced clinical-development requirements may lower entry barriers for selected programs, intensifying competition further. At the same time, patent disputes, reimbursement differences and region-specific substitution policies can materially alter commercialization timelines and market penetration. Companies concentrated in highly crowded molecules face increasing margin pressure and declining differentiation.
Technology and commercialization models are creating a second wave of disruption. Advanced cell-line engineering, intensified bioprocessing, continuous manufacturing, improved purification and digital quality systems can reduce production costs and strengthen supply scalability. Prefilled syringes, autoinjectors, subcutaneous formulations and other differentiated delivery formats are also enabling manufacturers to compete beyond price. Strategic licensing, co-development and regional commercialization partnerships are becoming increasingly important for reducing development risk and accelerating geographic expansion. Market leadership will increasingly favor companies with diversified pipelines, efficient manufacturing, reliable supply, strong payer relationships and exposure to high-value reference molecules with limited competitive density. Companies relying primarily on price discounting or mature, crowded biosimilar portfolios are likely to face greater margin and market-share pressure.
Latest FDA-Approved Biosimilars
| Biosimilar | Approval Date | Reference Product | Modality | Company | Therapeutic Area |
| Zimrixby (rituximab-cdxx) | July, 2026 | Rituxan (rituximab) | Monoclonal Antibody | Dr. Reddy's Laboratories SA | Oncology and Immunology |
| Garzulys (insulin aspart-fsan) | July, 2026 | Novolog (insulin aspart) | Rapid-Acting Insulin Analogue | Emerge Bioscience Pte. Ltd. | Diabetes |
| Ranluspec (ranibizumab-hkdz) | June, 2026 | Lucentis (ranibizumab) | Monoclonal Antibody Fragment | Lupin Limited | Ophthalmology |
Immgolis and Immgolis Intri (golimumab-sldi) | May, 2026 | Simponi and Simponi Aria (golimumab) | Monoclonal Antibody | Accord BioPharma Inc. | Immunology |
| Ennumo (pegfilgrastim-pccg) | May, 2026 | Neulasta (pegfilgrastim) | Recombinant Growth Factor | Accord BioPharma Inc. | Oncology Supportive Care |
| Langlara (insulin glargine-aldy) | April, 2026 | Lantus (insulin glargine) | Long-Acting Insulin Analogue | Sunshine Lake Pharma Co., Ltd. | Diabetes |
| Ponlimsi (denosumab-adet) | March, 2026 | Prolia (denosumab) | Monoclonal Antibody | Teva Pharmaceuticals, Inc. | Osteoporosis and Bone Health |
| Filkri (filgrastim-laha) | January, 2026 | Neupogen (filgrastim) | Recombinant Growth Factor | Accord BioPharma Inc. | Oncology Supportive Care |
Boncresa and Oziltus (denosumab-mobz) | December, 2025 | Prolia and Xgeva (denosumab) | Monoclonal Antibody | Amneal Pharmaceuticals LLC | Bone Health and Oncology |
| Nufymco (ranibizumab-leyk) | December, 2025 | Lucentis (ranibizumab) | Monoclonal Antibody Fragment | Zydus Lifesciences Global FZE | Ophthalmology |
| Armlupeg (pegfilgrastim-unne) | November, 2025 | Neulasta (pegfilgrastim) | Recombinant Growth Factor | Lupin Limited | Oncology Supportive Care |
| Poherdy (pertuzumab-dpzb) | November, 2025 | Perjeta (pertuzumab) | Monoclonal Antibody | Shanghai Henlius Biotech, Inc. | Oncology |
Osvyrti and Jubereq (denosumab-desu) | October, 2025 | Prolia and Xgeva (denosumab) | Monoclonal Antibody | Accord BioPharma Inc. | Bone Health and Oncology |
| Eydenzelt (aflibercept-boav) | October, 2025 | Eylea (aflibercept) | Recombinant Fusion Protein | Celltrion, Inc. | Ophthalmology |
Enoby and Xtrenbo (denosumab-qbde) | September, 2025 | Prolia and Xgeva (denosumab) | Monoclonal Antibody | Hikma Pharmaceuticals USA Inc. | Bone Health and Oncology |
Aukelso and Bosaya (denosumab-kyqq) | September, 2025 | Prolia and Xgeva (denosumab) | Monoclonal Antibody | Biocon Biologics Inc. | Bone Health and Oncology |
Bildyos and Bilprevda (denosumab-nxxp) | August, 2025 | Prolia and Xgeva (denosumab) | Monoclonal Antibody | Shanghai Henlius Biotech, Inc. | Bone Health and Oncology |
| Kirsty (insulin aspart-xjhz) | July, 2025 | Novolog (insulin aspart) | Rapid-Acting Insulin Analogue | Biocon Biologics Inc. | Diabetes |
| Starjemza (ustekinumab-hmny) | May, 2025 | Stelara (ustekinumab) | Monoclonal Antibody | Bio-Thera Solutions, Ltd. | Immunology |
| Jobevne (bevacizumab-nwgd) | April, 2025 | Avastin (bevacizumab) | Monoclonal Antibody | Biocon Biologics Inc. | Oncology |
Pipeline Analysis
| Company / Biosimilar Candidate | Reference Biologic | Molecule | Current Phase / Status | Therapeutic Area |
| Samsung Bioepis - SB27 | Keytruda | Pembrolizumab | Phase III | Oncology |
| Amgen - ABP 234 | Keytruda | Pembrolizumab | Phase III | Oncology |
| Celltrion - CT-P51 | Keytruda | Pembrolizumab | Phase III | Oncology |
| Amgen - ABP 206 | Opdivo | Nivolumab | Phase III | Oncology |
| Celltrion - CT-P44 | Darzalex | Daratumumab | Phase III | Oncology / Multiple Myeloma |
| Celltrion - CT-P53 | Ocrevus | Ocrelizumab | Phase III | Neurology / Multiple Sclerosis |
| Amgen - ABP 692 | Ocrevus | Ocrelizumab | Phase III | Neurology / Multiple Sclerosis |
| Celltrion - CT-P55 | Cosentyx | Secukinumab | Phase III | Immunology / Dermatology |
| Amgen - ABP 938 8 mg | Eylea HD | Aflibercept 8 mg | Phase III | Ophthalmology |
| Bio-Thera - BAT2306 | Cosentyx | Secukinumab | Phase III-Completed | Immunology / Dermatology |
| Bio-Thera - BAT3306 | Keytruda | Pembrolizumab | Phase I | Oncology |
| Henlius - HLX17 | Keytruda | Pembrolizumab | Phase I | Oncology |
| Henlius - HLX18 | Opdivo | Nivolumab | Phase I | Oncology |
| Henlius - HLX15-SC | Darzalex / Darzalex Faspro | Daratumumab | Phase I | Oncology / Multiple Myeloma |
Biosimilars Market BCG Matrix: Company Evaluation
STAR
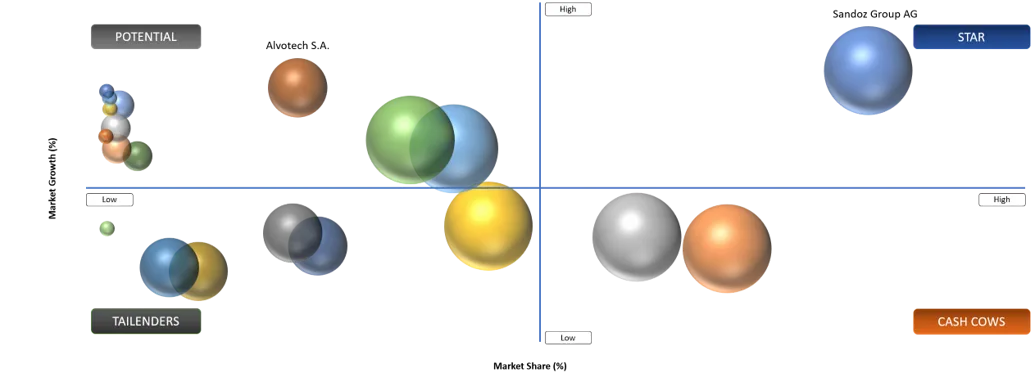
Sandoz Group AG, Amgen Inc., Celltrion, Inc., Samsung Bioepis Co., Ltd., Biocon Biologics Limited and Fresenius Kabi AG are positioned in the Star category based on broad commercial portfolios, global regulatory presence, established manufacturing capabilities and strong next-generation pipelines. Sandoz and Celltrion benefit from extensive international commercialization, while Samsung Bioepis and Biocon Biologics combine diversified molecule portfolios with strong development and manufacturing capabilities. Biocon Biologics currently reports 10 approved or commercial molecules across diabetes, oncology, immunology and ophthalmology, while Fresenius Kabi has six FDA-approved biosimilars and an expanding pipeline.
Amgen strengthens the group through its established biologics expertise and global commercial infrastructure. Continued Star positioning will depend on successful entry into upcoming high-value reference molecules, manufacturing economics, payer access, tender competitiveness, supply reliability and geographic expansion.
POTENTIAL
Alvotech S.A., Formycon AG, Shanghai Henlius Biotech, Inc., Bio-Thera Solutions, Ltd., Dr. Reddy's Laboratories Limited, Intas Pharmaceuticals Limited, Gedeon Richter Plc., Teva Pharmaceutical Industries Ltd., Lupin Limited and Zydus Lifesciences Limited are positioned in the Potential category based on expanding pipelines, increasing international approvals and growing commercialization partnerships.
Alvotech has one of the strongest emerging pipelines, spanning adalimumab, ustekinumab, denosumab, golimumab, aflibercept, omalizumab, pembrolizumab and several next-wave molecules. Formycon is strengthening its position through European launches and international licensing partnerships. These companies have significant upside potential as additional biologics lose exclusivity, but future positioning will depend on pipeline conversion, regulatory execution, manufacturing scale, launch timing, commercialization partnerships and the ability to achieve sustainable market share in increasingly competitive molecules.
Biosimilars Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Patent Expiries of High-Value Reference Biologics | 22.4% | High across North America, Europe and Asia Pacific | Oncology, immunology, ophthalmology and specialty biologics | Expands the addressable biosimilar pipeline and creates new commercialization opportunities around major loss-of-exclusivity events |
Growing Healthcare Cost-Containment and Payer Preference for Biosimilars | 19.6% | High across public and private healthcare systems | Hospital procurement, reimbursement, formulary inclusion and chronic biologic therapy | Accelerates biosimilar adoption by improving treatment affordability and supporting healthcare-system savings |
Expanding Regulatory Approvals and Streamlined Development Pathways | 17.8% | Strong across the United States, Europe and other regulated markets | New product approvals, pipeline development and geographic expansion | Reduces development uncertainty and supports faster entry of new biosimilar products |
Increasing Physician and Patient Acceptance | 15.3% | High in mature biosimilar markets and increasing in emerging markets | Oncology, immunology, diabetes, ophthalmology and long-term biologic treatment | Improves switching, prescribing confidence and sustained biosimilar penetration |
Driver: Patent Expiries of High-Value Reference Biologics
Patent expiries of high-value reference biologics are a major growth driver for the global biosimilars market, opening established therapeutic categories to new competition. As leading biologics across oncology, immunology, ophthalmology, hematology and other specialty areas lose exclusivity, biosimilar developers gain access to large patient populations and significant existing treatment demand. These expiries encourage pipeline investment, expand product availability and support lower-cost treatment alternatives for healthcare systems. Commercial success depends on early molecule selection, patent landscape assess.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
High Development and Manufacturing Complexity of Biosimilars | 18.7% | Development cost, analytical comparability, manufacturing consistency and scalability | Monoclonal antibodies, fusion proteins and other complex biosimilars | Raises entry barriers, extends development timelines and favors companies with advanced biologics manufacturing and analytical capabilities |
Aggressive Price Erosion and Intensifying Competition | 16.9% | Profitability, tender pricing, portfolio sustainability and return on investment | Mature biosimilar molecules across oncology, immunology and supportive care | Compresses margins, increases pressure on cost structures and reduces attractiveness of highly crowded reference molecules |
Patent Litigation and Intellectual Property Uncertainty | 15.2% | Launch timing, legal expenditure and commercialization planning | Biosimilars targeting high-value biologics approaching loss of exclusivity | Can delay market entry, increase development risk and weaken first-mover advantages |
Restraint: High Development and Manufacturing Complexity of Biosimilars
High development and manufacturing complexity is a major restraint for the global biosimilars market because these products require advanced analytical characterization, tightly controlled cell-culture processes, purification systems, formulation development and extensive comparability testing. Small process variations can affect product quality, consistency and regulatory outcomes, increasing technical risk and development expenditure. Manufacturers must also maintain validated facilities, robust quality systems and reliable scale-up capabilities across commercial production. These requirements create high barriers for smaller entrants and can extend development timelines. Companies with established biologics infrastructure, experienced regulatory teams, strong process-development capabilities and efficient manufacturing platforms are better positioned to manage these challenges.
Biosimilars Market Segment Analysis
The global Biosimilars market is segmented based on the product class, molecule complexity, manufacturing platform, therapeutic area, route of administration, distribution channel, end user and region.
Monoclonal Antibody Biosimilars
Monoclonal antibody biosimilars are assumed to dominate the global biosimilars market with approximately 56.8% share, equivalent to around US$19.6 billion in 2025. Their leadership is supported by broad use across oncology, immunology, ophthalmology and other high-value therapeutic areas, together with established biosimilar competition for molecules such as adalimumab, trastuzumab, rituximab and bevacizumab. Strong physician familiarity, large treated patient populations and extensive hospital and specialty-care utilization reinforce demand. Continued patent expiries, payer-driven switching, expanding formulary inclusion and wider geographic commercialization are expected to sustain the segment’s leading position.
Fusion Protein Biosimilars
Fusion protein biosimilars are assumed to be the fastest-growing product class, expanding at approximately 16.8% CAGR during 2026–2035. Growth is supported by increasing development activity around complex biologics used in immunology, ophthalmology and other specialty therapies, where patent expiries are creating new commercialization opportunities. Molecules such as etanercept and aflibercept demonstrate the growing relevance of this category, while additional fusion-protein targets are expected to enter biosimilar pipelines. Higher technical barriers, complex manufacturing requirements and comparatively lower competitive density can also improve differentiation potential. Future growth will depend on regulatory execution, manufacturing scalability, pricing strategy and payer acceptance.
Biosimilars Market Geographical Penetration
U.S. Biosimilars Market Landscape
The United States is one of the most influential biosimilars markets due to its large biologics expenditure, expanding approval pipeline, and growing payer pressure to reduce drug costs. As of June 2026, 96 biosimilars across 21 reference molecules had received FDA approval, with 71 products launched commercially. Biosimilars achieved an average market share of about 47% within five years of launch, while average sales prices declined substantially. Regulatory streamlining in 2026 is also expected to reduce development costs and accelerate market entry. Future growth will depend on interchangeability, payer contracting, formulary access, physician adoption and competition around upcoming high-value biologic patent expiries.
Germany Biosimilars Market Outlook
Germany remains one of Europe’s most important biosimilars markets, supported by mature reimbursement systems, strong physician familiarity and extensive use of competitive contracting and substitution mechanisms. Biosimilars accounted for more than half of biologics-market revenue across pharmacy and hospital channels during the first half of 2025. In 2026, expanded substitution rules are shifting more switching decisions toward pharmacies, while rebate contracts and tender mechanisms are intensifying price competition. Germany therefore represents an important benchmark for mature-market biosimilar adoption. Future opportunities will depend on portfolio breadth, tender competitiveness, reliable supply, payer relationships and the ability to maintain commercial sustainability despite increasing pricing pressure.
South Korea Biosimilars Market Outlook
South Korea is a strategically important global biosimilars hub due to its advanced biologics manufacturing infrastructure and the international presence of companies such as Celltrion and Samsung Bioepis. Celltrion currently commercializes 11 biosimilars globally and plans to expand its portfolio significantly, supported by continued investment in manufacturing capacity and direct commercialization. Samsung Bioepis is also strengthening its next-generation pipeline through global development and commercialization partnerships, including collaborations covering multiple future biosimilar candidates. South Korea’s competitive advantage lies in integrated development, regulatory expertise, large-scale manufacturing and export-oriented commercialization. Continued investment in production capacity, complex molecules and global partnerships should reinforce the country’s role in future biosimilar supply and innovation.
Biosimilars Market Competitive Landscape
- The global biosimilars market is characterized by competition among established biologics manufacturers, dedicated biosimilar developers and emerging regional players. Sandoz Group AG, Amgen Inc., Celltrion, Inc., Samsung Bioepis Co., Ltd., Biocon Biologics Limited and Fresenius Kabi AG maintain strong positions through broad commercial portfolios, global regulatory approvals, integrated manufacturing and extensive distribution capabilities. Sandoz reported USD 3.3 billion in biosimilar sales in 2025 and maintains 27 pipeline candidates, while Celltrion commercializes 11 biosimilars and is expanding toward 41 products by 2038.
- Competition is increasingly shifting from price-based entry toward portfolio breadth, launch timing, manufacturing economics, differentiated formulations, payer access and supply reliability. Companies such as Alvotech S.A., Formycon AG, Shanghai Henlius Biotech, Inc. and Bio-Thera Solutions, Ltd. are strengthening competitive intensity through next-generation pipelines and international licensing strategies. Biocon Biologics is expanding across oncology, immunology, diabetes, ophthalmology and bone health, while Celltrion is pursuing new molecules including pembrolizumab, daratumumab, ocrelizumab and secukinumab. Future leadership will depend on successful patent-expiry positioning, regulatory execution, cost-efficient manufacturing, tender competitiveness, formulary access, strategic partnerships and the ability to commercialize complex biosimilars across multiple regions.
Key Companies of the Biosimilars Market
- Sandoz Group AG (Switzerland)
- Amgen Inc. (United States)
- Celltrion, Inc. (South Korea)
- Samsung Bioepis Co., Ltd. (South Korea)
- Biocon Biologics Limited (India)
- Fresenius Kabi AG (Germany)
- Pfizer Inc. (United States)
- Alvotech S.A. (Iceland)
- STADA Arzneimittel AG (Germany)
- Organon & Co. (United States)
- Dr. Reddy's Laboratories Limited (India)
- Shanghai Henlius Biotech, Inc. (China)
- Bio-Thera Solutions, Ltd. (China)
- Intas Pharmaceuticals Limited (India)
- Gedeon Richter Plc. (Hungary)
- Formycon AG (Germany)
- Teva Pharmaceutical Industries Ltd. (Israel)
- Lupin Limited (India)
- Zydus Lifesciences Limited (India)
- Polpharma Biologics Group B.V. (Netherlands)
Global Biosimilars Market Major Pain Points
- Complex Regulatory and Market Access Requirements: Differences in approval pathways, interchangeability rules, substitution policies, reimbursement systems and tender structures across countries complicate global commercialization strategies.
- High Development and Manufacturing Costs: Biosimilars require advanced analytical characterization, controlled biologics manufacturing, comparability studies and validated quality systems, creating substantial capital and technical barriers.
- Aggressive Price Erosion: Multiple competitors targeting the same reference biologic can trigger rapid discounting, reducing margins and weakening returns on development investment.
- Patent Litigation and Launch Uncertainty: Patent disputes, exclusivity considerations and legal challenges can delay commercialization and increase development risk for biosimilar manufacturers.
- Uneven Physician and Patient Acceptance: Concerns around switching, interchangeability and treatment continuity can slow adoption, particularly in chronic and specialty therapies.
- Supply Reliability and Capacity Constraints: Biologics manufacturing complexity, limited redundancy and production disruptions can affect product availability, tender performance and healthcare-provider confidence.
- Intensifying Competition in Mature Molecules: Crowded markets for established biosimilars increase pressure on pricing, differentiation and market share, making molecule selection and launch timing increasingly critical.
Biosimilars Market Recent Developments
- August 2026: Alvotech announced that the FDA accepted its BLA for AVT80, a proposed interchangeable biosimilar to Entyvio (vedolizumab) in prefilled syringe and autoinjector presentations, strengthening its immunology pipeline.
- August 2026: Samsung Bioepis initiated a Phase I clinical trial for SB35, its proposed biosimilar to Taltz (ixekizumab), expanding its development pipeline in autoimmune and inflammatory diseases.
- August 2026: Alvotech entered a licensing and commercialization agreement with Lotus Pharmaceutical for proposed biosimilars to Imfinzi (durvalumab) and Hemlibra (emicizumab) across the United States and selected Asian markets.
- July 2026: Formycon and OneSource Specialty Pharma established a strategic manufacturing partnership covering integrated drug-substance and drug-product production for Formycon’s global biosimilar programs.
- June 2026: Samsung Bioepis reported positive preliminary Phase I and Phase III results for SB27, its proposed Keytruda (pembrolizumab) biosimilar, with both studies meeting their primary endpoints.
- May 2026: The FDA approved Immgolis and Immgolis Intri, the first interchangeable biosimilars to Simponi and Simponi Aria (golimumab), expanding biosimilar competition in rheumatoid arthritis and ulcerative colitis.
- May 2026: Samsung Bioepis launched its ustekinumab biosimilar in Japan, marking the company’s first commercial biosimilar launch in the Japanese market through its partnership with Nipro Corporation.
- March 2026: The FDA issued draft guidance proposing further streamlining of biosimilar development, including reduced clinical pharmacokinetic testing where scientifically justified, potentially lowering development costs and accelerating market entry.
Analyst View / Opinion on Biosimilars Market
- The biosimilars market is shifting from a primarily cost-saving alternative toward a strategic component of biologic treatment access, supported by expanding approvals, patent expiries and increasing payer adoption.
- Oncology and immunology will remain major revenue contributors, while ophthalmology, bone health, neurology, diabetes and other specialty therapies are creating the next wave of commercial opportunities.
- Competitive success will increasingly depend on molecule selection, launch timing, regulatory execution, manufacturing efficiency, supply reliability and the ability to secure strong payer, formulary and tender access.
- Development economics are improving as regulators place greater emphasis on advanced analytical comparability and more streamlined clinical requirements, potentially reducing timelines and capital intensity for selected biosimilar programs.
- Prefilled syringes, autoinjectors, subcutaneous formulations and other differentiated presentations will become more important as manufacturers seek to compete beyond price and improve patient and provider convenience.
- Sustainable market leadership will depend on diversified pipelines, cost-efficient manufacturing, geographic expansion, strategic partnerships and disciplined pricing, with companies targeting high-value, less-crowded reference molecules positioned to capture stronger long-term returns.
Biosimilars Market Target Audience
| INDUSTRY | WHO SHOULD BUY THIS REPORT? | REASON TO BUY THIS REPORT |
| Biosimilar Manufacturers and Developers | Biosimilar developers, biologics manufacturers, pharmaceutical companies and biotechnology companies | Assess molecule-level opportunities, patent-expiry windows, competitive intensity, pipeline positioning, manufacturing requirements and regional commercialization potential. |
| Originator Biologic Companies | Reference biologic manufacturers, portfolio strategy teams and lifecycle-management teams | Evaluate biosimilar entry risk, expected competitive pressure, price erosion, market-share exposure and defensive lifecycle strategies. |
| Biologics Contract Manufacturers | Contract development and manufacturing organizations, fill-finish providers and bioprocessing companies | Identify outsourcing demand, capacity requirements, manufacturing-platform opportunities and emerging biosimilar pipelines requiring commercial-scale production. |
| Healthcare Providers | Hospitals, specialty clinics, infusion centers, physician groups and health systems | Understand biosimilar availability, therapeutic adoption, switching dynamics, administration formats, supply reliability and potential treatment-cost implications. |
| Payers and Procurement Organizations | Health insurers, pharmacy benefit managers, government payers, hospital procurement teams and tender authorities | Benchmark biosimilar pricing, reimbursement trends, tender competition, formulary strategies and potential healthcare-system savings. |
| Distributors and Specialty Pharmacies | Pharmaceutical distributors, wholesalers, hospital pharmacies and specialty pharmacy networks | Evaluate product-launch pipelines, distribution opportunities, therapy-area demand, inventory requirements and supplier positioning. |
| Investors and Financial Institutions | Private equity firms, venture capital investors, institutional investors, investment banks and strategic investors | Assess high-value molecule opportunities, competitive pipelines, commercialization risk, manufacturing economics and potential investment or acquisition targets. |
Why Choose DATAM?
- Data-Driven Insights: Access granular biosimilars market intelligence covering market size, reference molecules, product classes, therapeutic areas, manufacturing platforms, regional adoption, pricing, reimbursement, tender dynamics, competitive positioning, patent-expiry opportunities and country-level regulatory developments, supported by primary interviews with industry experts and validated secondary research.
- Post-Purchase Support and Expert Analyst Consultations: Engage directly with our analysts for customized guidance on molecule prioritization, market entry, portfolio expansion, competitor benchmarking, pricing strategy, commercialization planning, manufacturing requirements, payer access and geographic expansion across established and emerging biosimilar markets.
- White Papers and Case Studies: Gain access to focused analyses covering biosimilar launch strategies, patent-expiry opportunities, pricing erosion, interchangeability, payer adoption, manufacturing economics, regulatory pathways and successful commercialization models across major therapeutic areas and regions.
What DATAM Uniquely Provides
- In-depth segmentation of the biosimilars market by product class, reference molecule, molecule complexity, manufacturing platform, therapeutic area, route of administration, distribution channel, end user and region.
- Competitive analysis of leading biosimilar companies covering approved products, development pipelines, reference molecules, manufacturing capabilities, regulatory approvals, geographic presence, pricing approach, licensing activity, commercialization strategy and portfolio positioning.
- Comprehensive assessment of biosimilar demand across oncology, immunology, ophthalmology, diabetes, hematology, bone health, neurology, endocrinology and other specialty therapeutic areas, supported by payer, provider and patient adoption trends.
- Actionable intelligence on patent-expiry opportunities, pricing erosion, reimbursement, tender dynamics, interchangeability, substitution policies, regulatory pathways, manufacturing economics, supply reliability, strategic partnerships, licensing agreements and investment opportunities.
- Analyst forecasts highlighting high-potential reference molecules, less-crowded development opportunities, emerging therapeutic areas, country-level expansion potential, future competitive intensity and commercialization opportunities across established and developing biosimilar markets.



























































